Interest Mathematics / Cash Flow Architecture
How to Calculate Your Daily Interest Bleed on Credit Cards
Most borrowers look at their credit card statement once a month, see an abstract percentage like 24.99% APR, and pay the minimum balance without realizing that interest does not accrue monthly. It charges you by the hour.
If you have ever felt like you are making substantial monthly payments only for your principal balance to barely budge, you are experiencing interest bleeding. Credit card issuers do not wait for your billing cycle to close to calculate what you owe. They compound interest daily based on your average daily balance.
To outsmart high-interest debt, you have to transition from managing debt by arbitrary monthly minimums to understanding your daily dollar bleed. Once you convert an abstract annual percentage rate (APR) into actual cash vanishing every 24 hours, your entire repayment sequence changes.
The Daily Interest Bleed Formula
To calculate the exact dollar cost your balances drain while you sleep, use this three-step formula:
Step 1: Calculate Your Daily Periodic Rate (DPR)
DPR = APR ÷ 365
Step 2: Calculate Your Daily Interest Dollar Bleed
Daily Interest ($) = Current Balance × DPR
Step 3: Calculate Your Monthly Compounded Leakage
Monthly Bleed ($) = Daily Interest ($) × 30
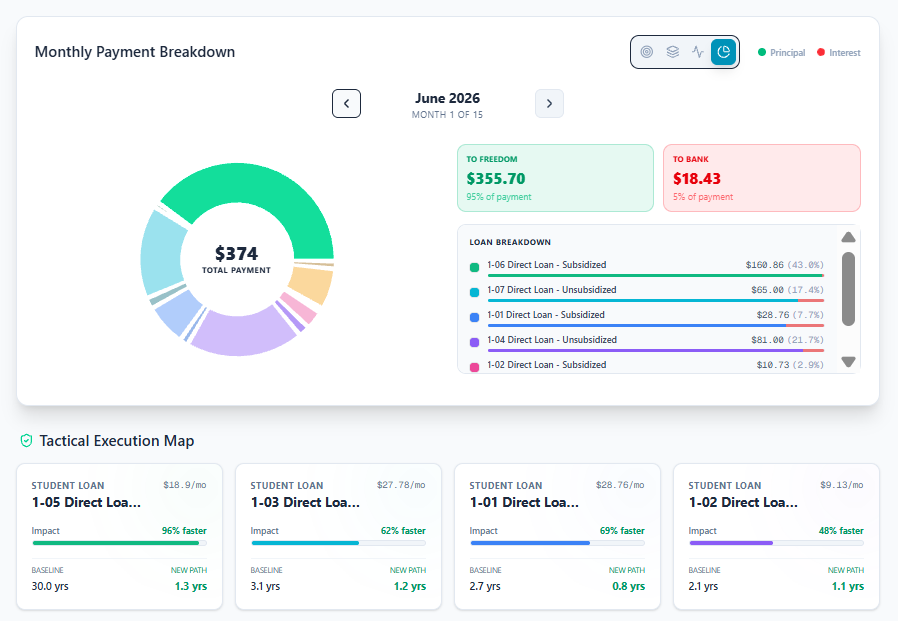
Figure 1: Visualizing how monthly payments are silently cannibalized by daily interest bleed before reducing principal.
Real-World Example: The “Sneaky” Balance Trap
Consider a borrower holding two credit cards. Conventional wisdom often misleads borrowers on which card is actively doing the most damage to their cash flow:
| Account | Balance | APR | Daily Rate (DPR) | Daily Interest Bleed | 30-Day Interest Bleed |
|---|---|---|---|---|---|
| Card A (Store Card) | $2,500 | 29.99% | 0.0821% | $2.05 / day | $61.50 / mo |
| Card B (Travel Card) | $16,800 | 22.49% | 0.0616% | $10.35 / day | $310.50 / mo |
The standard Avalanche method tells you Card A is the top priority because 29.99% is higher than 22.49%. The Snowball method also picks Card A because $2,500 is smaller than $16,800.
However, looking through the lens of daily interest bleed reveals that Card B is draining $10.35 every single day ($310.50/month) compared to Card A’s $2.05/day. Card B is responsible for 83% of your monthly wealth destruction. Ignoring Card B’s volume causes financial fatigue because your net worth bleeds out five times faster on the larger balance.
Figure 2: Comparing Snowball, Avalanche, and the Dynamic Blitz protocol to isolate and attack highest daily interest leakage.
The Dynamic Blitz Strategy: Targeting Dollar Bleed
Rather than locking yourself into rigid binary strategies, the Dynamic Blitz protocol recalculates your payoff priority each month based on actual interest dollars accrued per day.
Standard APR Targeting
Percentage-First Focus
Treats a 29% APR on a $500 balance as higher priority than a 24% APR on a $25,000 balance, ignoring the fact that the larger balance bleeds $16.44/day versus $0.40/day.
Dynamic Blitz Protocol
Dollar-Bleed Suppression
Targets the exact account generating the largest dollar amount of daily interest. As balances drop, the priority automatically recalibrates to minimize total lifetime interest paid.
1. Audit Daily Interest Across All Accounts
Multiply each card’s current balance by its APR and divide by 365. Sum the daily totals to identify your household’s total daily bleed rate.
2. Funnel Extra Capital to the Top Daily Bleeder
Maintain contractual minimums across secondary cards, but direct 100% of any freed cash flow or extra payment injections to the primary daily dollar drain.
3. Simulate Mid-Month Extra Payments
Because interest compounds daily, making an extra payment on Day 5 of your billing cycle instead of Day 28 saves 23 days worth of compounding interest on that principal chunk.
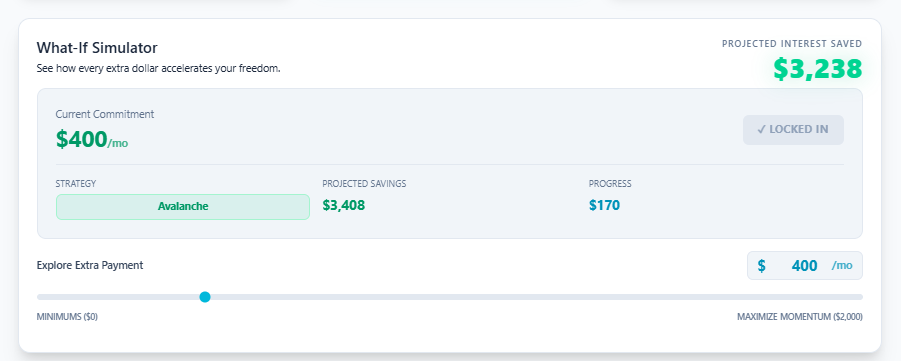
Figure 3: Simulating how lump-sum and recurring extra payments accelerate your debt-free date and slash lifetime interest.
Frequently Asked Questions
Does making two payments a month reduce daily interest bleed?
Why does my statement show a different interest charge than my formula?
How does 0% balance transfer promo interest work?
Interactive 12-Month Payoff Blueprint
Stop guessing your payoff timeline. Measure your exact daily interest velocity and map your fastest path to zero.
We engineered LEVEL Debt-Free Architect to calculate your daily interest bleed, run side-by-side strategy simulations (Snowball, Avalanche, Dynamic Blitz), and generate an interactive 12-month construction blueprint—100% private, with zero bank logins or Plaid sync required.