
Credit Utilization Ratio Explained: The 30% Myth, Exact Calculation & How to Maximize Your Credit Score
Credit utilization drives nearly one-third of your entire credit score. Yet millions of borrowers follow the conventional “under 30%” guideline, unknowingly bleeding 40 to 60 points off their credit profile. Here is how scoring models actually calculate revolving risk, why single cards secretly torpedo scores, and how to engineer top-tier credit.
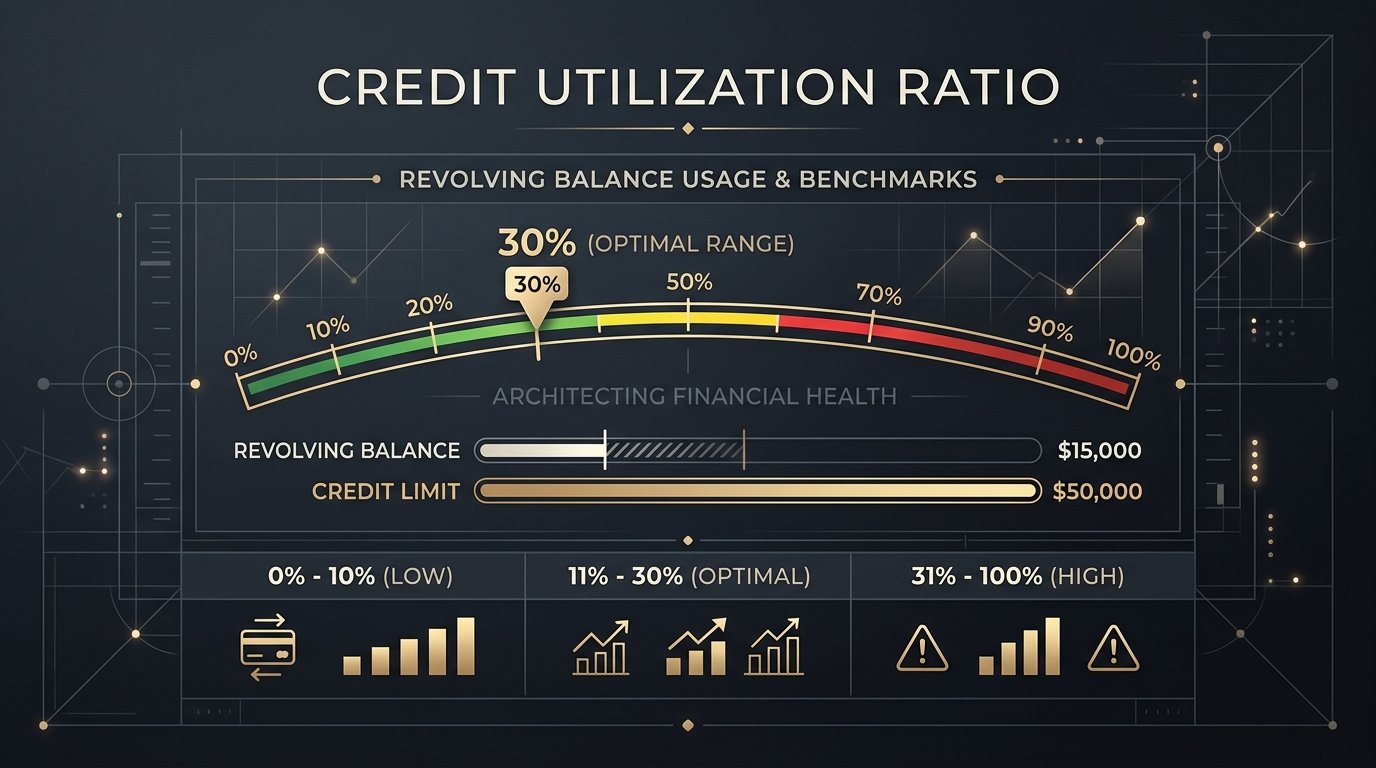
If you have ever paid off a credit card balance and watched your credit score jump overnight—or charged an emergency expense and watched your score violently drop 45 points within 48 hours—you have experienced the volatile mechanics of the credit utilization ratio.
After your payment track record (which commands 35% of your FICO score), credit utilization represents the single largest lever in modern credit scoring, dictating 30% of your total score under the “Amounts Owed” category. In practical terms, that means roughly 165 points in a standard 300–850 FICO score range are governed directly by how much revolving balance you report relative to your credit limits.
Yet despite its massive impact on mortgage rates, auto loan approvals, and insurance premiums, credit utilization is widely misunderstood. Pervasive personal finance myths—such as the belief that maintaining a 29% balance is “good” or that paying off a card to exactly $0 is always optimal—cause borrowers to leave dozens of points on the table.
In this guide, we break down the exact mathematical formula, debunk the 30% guideline, explain the critical difference between aggregate and per-card utilization, and reveal the step-by-step strategies sophisticated borrowers use to optimize their scores.
What is Credit Utilization Ratio? The Mathematical Formula
Your credit utilization ratio is the percentage of your total available revolving credit that you are currently using. Revolving credit accounts include traditional credit cards, retail store credit cards, and personal lines of credit (including Home Equity Lines of Credit, or HELOCs, depending on how the lender reports them).
It does not include installment loans, such as fixed mortgages, auto financing, student loans, or personal term loans. While installment balances factor into other elements of your credit report (such as original balance vs. current loan amortization), they are completely excluded from revolving utilization calculations.
Example: If you have three credit cards with a combined credit limit of $20,000, and your total reported balances across all three cards equal $3,000, your aggregate credit utilization ratio is exactly ($3,000 ÷ $20,000) × 100% = 15.0%.
While the overall aggregate formula is simple, scoring algorithms (such as FICO Score 8, FICO Score 9, FICO Score 10, and VantageScore 3.0/4.0) do not stop at a single calculation. They run dual-layer evaluations that examine both your overall portfolio and every individual card you carry.
The “30% Rule” Is a Myth: What Scoring Models Actually Reward
Every generic credit advice article repeats the same tired maxim: “Keep your credit utilization below 30%.”
This advice is dangerous because it mistakes a damage threshold for a best practice. Staying below 30% simply prevents catastrophic scoring penalties; it does not maximize your score.
FICO algorithms do not treat utilization as a binary pass/fail test at the 30% mark. Instead, credit utilization operates along a continuous, non-linear decay curve with distinct penalty cliffs. The moment your aggregate utilization crosses approximately 9.5%, your FICO score begins losing points. Crossing 29.5% triggers another sharp penalty tier, and crossing 49.5% triggers another.
| Utilization Bracket | FICO Score Risk Tier | Estimated Point Impact | Algorithmic Assessment |
|---|---|---|---|
| 0.0% (All Cards $0) | Minor Penalty | -12 to -25 pts | Penalty for “no recent revolving usage” activity |
| 0.1% – 5.9% | Optimal / Top Tier | +40 to +60 pts (Peak) | FICO “Exceptional” sweet spot (AZEO target) |
| 6.0% – 9.9% | Excellent | +30 to +45 pts | Minimal risk; ideal for day-to-day cardholders |
| 10.0% – 29.9% | Moderate / Average | Baseline (0 to -15 pts) | Acceptable for standard approvals; suboptimal for tier-1 rates |
| 30.0% – 49.9% | Elevated Risk | -25 to -45 pts | Warning flags trigger; interest rate tiers worsen |
| 50.0% – 89.9% | High Risk | -50 to -90 pts | Lenders view borrower as cash-flow constrained |
| 90.0% – 100%+ | Severe Default Risk | -90 to -130+ pts | Maxed-out distress flag; algorithmic score collapse |
According to data released by FICO, consumers in the highest credit tier (FICO 800+) carry an average revolving utilization ratio of 5.8% to 7.0%. If you are sitting at 28% utilization believing you are in the “safe zone,” your score is likely suppressed by 30 to 50 points compared to where it would sit under 6%.
The Dual-Layer Trap: Aggregate vs. Per-Card Utilization
One of the most expensive misunderstandings in personal credit management is the belief that only your total portfolio utilization matters. In reality, modern credit scoring algorithms evaluate two distinct ratios simultaneously:
- Aggregate Utilization: The sum of all balances divided by the sum of all credit lines.
- Per-Card (Individual) Utilization: The balance on each specific credit card divided by that specific card’s limit.
If either ratio breaches high thresholds, the algorithm applies a scoring penalty. Consider this real-world scenario of a borrower named Marcus who holds $30,000 across three credit lines:
| Account | Credit Limit | Current Balance | Card Utilization | Scoring Status |
|---|---|---|---|---|
| Card A (Travel Rewards) | $5,000 | $4,500 | 90.0% | Critical Penalty |
| Card B (Cashback) | $10,000 | $200 | 2.0% | Optimal |
| Card C (Retail Card) | $15,000 | $300 | 2.0% | Optimal |
| Total Portfolio | $30,000 | $5,000 | 16.6% | Moderate Aggregate |
Looking at aggregate utilization alone, Marcus looks healthy at 16.6%. But because Card A is pushed to 90% of its credit line, FICO’s risk engine interprets this as a red flag for acute liquidity distress. Marcus’s score will drop substantially despite his total utilization sitting well below the 30% rule.
The Per-Card Bottleneck Principle
A single card maxed out at 85% or 90% utilization can wipe out up to 45 points from your credit score, even if all your other cards have zero balances and your overall portfolio utilization is under 10%. When planning debt payoff, targeting cards hovering above 50% or 80% yields immediate scoring relief.
The Calendar Trap: Statement Closing Date vs. Payment Due Date
Every month, millions of financially responsible people pay their credit card balances in full before the due date, never incurring a penny of interest, yet cannot understand why their credit monitoring reports 60% or 70% utilization.
The culprit is the mismatch between your Statement Closing Date and your Payment Due Date.
The Anatomy of a Credit Reporting Cycle
In the timeline above, you acted with complete financial discipline: you paid the entire statement balance by the due date. However, during the entire 30 days between statements, credit bureaus registered an 80% utilization ratio on that card. If a mortgage lender pulled your credit on Day 35, they evaluated a borrower carrying high-risk revolving utilization.
The Pre-Statement Paydown Fix
To ensure your reported utilization reflects your true financial discipline, pay down the majority of your balance 3 to 5 business days before your Statement Closing Date. Leave a nominal $10 to $25 balance so the statement generates with a 1% utilization ratio, then allow autopay to clear the remainder on the due date.
Advanced Score Engineering: The AZEO Strategy
When preparing for major underwriting events—such as applying for a 30-year fixed mortgage, refinancing debt, or requesting high-tier business credit—seasoned credit architects use the AZEO (All Zero Except One) method.
The strategy exploits a peculiar quirk in FICO’s algorithm: the “All-Zero” Penalty.
When every single revolving credit card reports a $0 balance on its statement date, FICO algorithms cannot observe recent active management of revolving credit lines. In response, the scoring model deducts between 12 and 25 points for inactivity. While counter-intuitive, showing a tiny active balance is mathematically superior to reporting zero across the board.
How to Execute the AZEO Method:
- Audit Your Statement Dates: Log into every credit card account and record the exact monthly Statement Closing Date (not the payment due date).
- Pay All Cards to $0 Before Statement Generation: For all cards except one, submit payments so the balance on the statement closing date is exactly $0.00.
- Select One “Anchor” Card: Choose a major national bank card (e.g., Chase, Citi, Discover) that is a standard revolving credit card (not an American Express charge card, which does not report a credit limit).
- Report Between 1% and 2% on the Anchor Card: Allow a small balance—typically between $15 and $50—to post to the statement. This registers as an ultra-low, active utilization tier without tripping any penalty threshold.
- Pay Off the Anchor Card Immediately After the Statement Posts: Once the statement generates, pay the balance off in full before the due date to avoid interest charges.
Borrowers who shift from 35% utilization across multiple cards to the AZEO method routinely observe immediate score surges of 35 to 70 points within a single reporting cycle.
How Debt Payoff Directly Repairs Utilization
One of the most encouraging aspects of credit utilization is that under standard scoring models like FICO Score 8, utilization has no memory.
Unlike late payments or collection accounts (which remain on your credit report for up to 7 years), utilization is purely a point-in-time calculation. As soon as your card issuers report lower balances to the credit bureaus—which typically happens once every 30 days—your score recalculates immediately based on the new numbers. Last month’s 85% utilization vanishes completely from your FICO 8 score calculation.
As we detailed in our guide on whether paying off debt raises your credit score, eliminating revolving balances creates a massive two-fold victory: it stops daily compounding interest bleed while simultaneously unlocking the highest credit score tiers.
Two Critical Traps to Avoid During Debt Payoff:
- Trap #1: Closing Accounts Once Paid to Zero. When people finish paying off an aggressive debt payoff sprint, their first emotional instinct is often to close the credit card. Doing so immediately erases that card’s credit limit from your total available credit denominator. If you have $10,000 in balances across two cards with $10,000 limits each ($20,000 total limit = 50% utilization), and you close one card, your total limit collapses to $10,000, catapulting your remaining utilization to 100%! Keep paid-off accounts open with a small automated recurring charge (like a streaming subscription) to preserve credit limits and credit history length.
- Trap #2: Requesting Credit Limit Increases at the Wrong Time. Increasing your credit limit reduces utilization mathematically without paying off debt. However, requesting a limit increase when your accounts already carry high utilization or recent missed payments often triggers a hard credit inquiry or an outright rejection. Optimize your existing balances first before requesting line expansions.
Tired of Managing Minimums and Playing Credit Score Defense?
Credit utilization is simply a symptom of revolving debt. Eliminate the balance, and your credit score takes care of itself. Model your exact debt-free date, calculate your daily interest bleed, and engineer your mathematical payoff roadmap.
Architect Your Debt Payoff Plan