Liability Architecture / Strategy Matrix
Consolidation Loan vs. Balance Transfer vs. Paying One by One
When facing $20,000 to $40,000 across multiple high-interest credit cards, you reach a major crossroad: Should you take out a personal consolidation loan, apply for a 0% balance transfer card, or aggressively pay down each card one by one?
The financial services industry heavily promotes consolidation loans and balance transfer cards as magical “silver bullets.” But behind every debt product lies origination fees, balance transfer penalties, and the catastrophic risk of re-leveraging your newly emptied credit cards.
If you are deciding between a debt consolidation loan vs paying off one by one (or using a balance transfer), you need an honest, mathematical breakdown of the true costs, psychological traps, and long-term interest savings of all three methods.
The 3 Payoff Paths Analyzed on a $30,000 Debt Portfolio
To see how each method performs in the real world, let’s examine a typical $30,000 multi-card portfolio (as explored in how to pay off $30k in credit card debt) across three accounts with a 25.5% average APR:
Option 01
The Personal Debt Consolidation Loan
You apply for a single $30,000 personal installment loan at a fixed 12.5% APR over 36 months to wipe out all credit cards in one stroke.
The Hidden Costs: Most lenders charge a 3% to 6% origination fee ($900 to $1,800), which is deducted from your payout or added directly to your principal. If your credit score is below 720, your interest rate may exceed 16%–22%, significantly reducing your savings.
The Relapse Risk: Emptying your credit cards provides an immediate emotional relief without fixing the underlying cash flow system. Without closing the cards, over two-thirds of borrowers re-accumulate debt within two years.
Option 02
The 0% Balance Transfer Card Strategy
You apply for a 0% introductory APR credit card with a 15-month promotional window to pause interest compounding.
The Hidden Costs: Balance transfer cards charge an immediate 3% to 5% transfer fee ($900 to $1,500 on $30k). Furthermore, issuers rarely grant a $30,000 credit limit on a single card—most borrowers only get approved for $5,000 to $8,000, leaving the remaining $22,000+ continuing to bleed daily interest (see daily interest bleed mechanics).
The Expiration Cliff: If any balance remains when Month 15 ends, the rate spikes to 28%–30% APR (sometimes retroactively under deferred interest terms).
Option 03
Strategic Cash Flow Routing (Paying One by One with Blitz)
You keep your accounts where they are, pay contractual minimums across secondary cards, and direct 100% of your surplus cash flow to the single highest daily dollar drain using the Blitz Protocol.
The Advantages: $0 in upfront fees, zero hard inquiries on your credit, zero risk of putting a spouse’s credit score on the line, and permanent behavioral conditioning that ensures you never return to debt.
The Math: Using a debt payoff calculator with extra payments, committing $1,400/mo clears all $30,000 in 25 months and saves $19,900+ in interest with zero fee drag.
Figure 1: Comparing one-by-one strategic routing against static balance ordering.
Side-by-Side Comparison: Consolidation vs. Balance Transfer vs. One by One
| Metric / Factor | Personal Consolidation Loan | 0% Balance Transfer Card | Paying One by One (Blitz Protocol) |
|---|---|---|---|
| Upfront Fees | 3%–6% Origination ($900–$1,800) | 3%–5% Transfer Fee ($900–$1,500) | $0.00 (Zero Fees) |
| Credit Check Required | Hard Inquiry (Dings Score) | Hard Inquiry (New Account) | None (Uses Existing Accounts) |
| Portfolio Coverage | Covers all $30k (if approved) | Partial ($5k–$8k limit cap) | 100% Full Portfolio Coverage |
| Relapse / Re-Debt Risk | High (Empty cards tempt new debt) | Moderate (Multiple active accounts) | Lowest (Builds lasting discipline) |
| Payoff Flexibility | Fixed installment schedule | Rigid 12–18 month cliff | Dynamic monthly re-allocation |
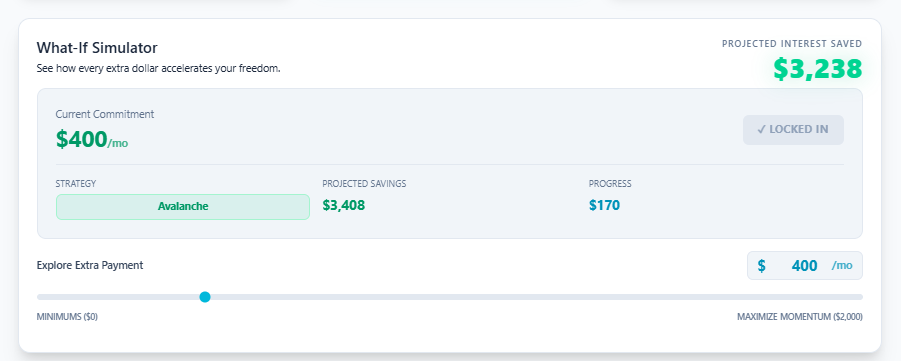
Figure 2: Testing extra payment injections to accelerate one-by-one repayment with zero loan fees.
The Decision Matrix: Which Path Should You Choose?
Choose a Personal Loan ONLY If:
You can qualify for an interest rate under 10% APR with zero origination fee, your monthly cash flow is severely restricted, and you immediately freeze/cut the original credit cards to prevent re-leveraging.
Choose a Balance Transfer ONLY If:
You have a single small sub-balance ($3,000 to $6,000) that you have the guaranteed cash flow to pay off 100% within the 12-month promotional window before interest spikes.
Choose Paying One by One (Recommended) If:
You have steady household income and surplus cash flow ($400+/mo). Paying one by one with a dynamic strategy avoids all loan fees, protects your spouse’s credit score, and rapidly knocks out accounts with zero third-party dependencies (see when to apply dynamic strategies).
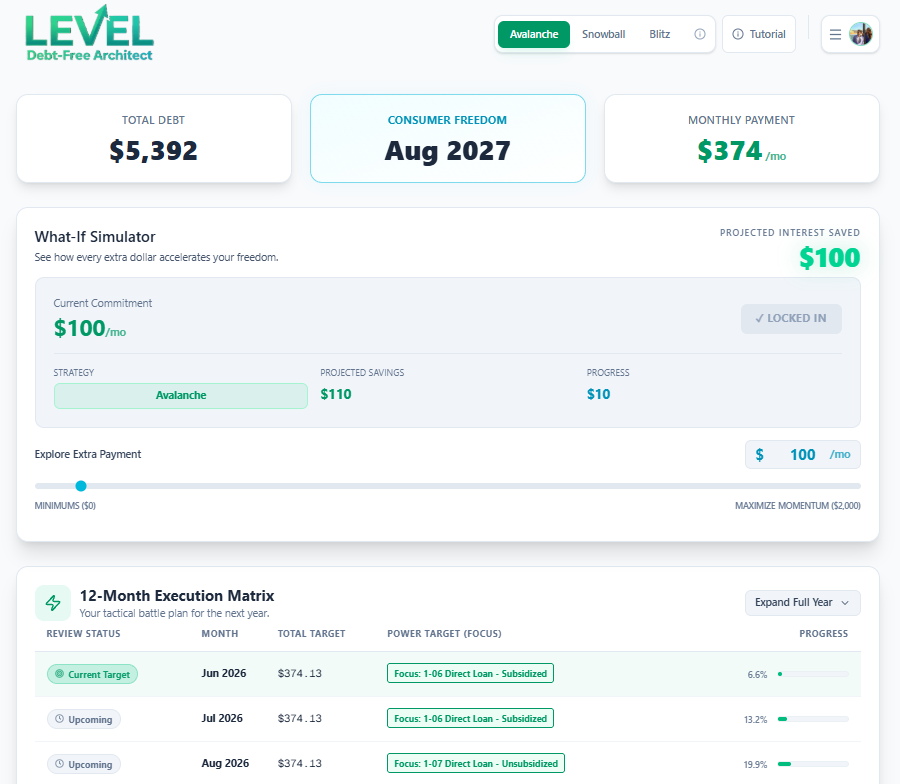
Figure 3: Tracking sequential one-by-one payoff milestones across a visual 12-month construction roadmap.
Frequently Asked Questions
Should I use my spouse’s 750+ credit score to get a consolidation loan?
Does closing paid-off credit cards hurt my credit score?
How does the Dynamic Blitz protocol beat a consolidation loan?
Interactive Payoff Strategy Blueprint
Skip the loan origination fees. Engineer your custom path to zero.
Compare your repayment options today with LEVEL Debt-Free Architect. Run side-by-side strategy simulations (Snowball, Avalanche, Dynamic Blitz), test what-if payment injections, and build your visual 12-month construction roadmap—100% private, with zero bank sync required.