Banking Mechanics / Compounding Mathematics
What is the Daily Balance Method for Calculating Interest?
Most cardholders assume credit card interest is calculated simply on their ending monthly balance. In reality, card issuers use the daily balance method—calculating interest on your exact ledger balance every single day of the month.
If you carry a credit card balance from month to month, you have probably noticed that your monthly interest charge never matches a straightforward percentage of your statement balance. That is because nearly all major banks (Chase, Citi, Capital One, Discover, Amex) use the Daily Balance Method (or Average Daily Balance) to determine your finance charges.
Understanding how this calculation functions behind the scenes is crucial: it reveals why the timing of your payments matters just as much as the amount, and why making extra payments mid-cycle saves far more money than waiting for your due date (as explored in our guide on calculating daily interest bleed).
How the Daily Balance Method Works: Step-by-Step
To calculate interest under the daily balance method, card issuers follow a 4-step mathematical sequence throughout your 28- to 31-day billing cycle:
Step 1: Calculate Your Daily Periodic Rate (DPR)
DPR = APR ÷ 365 (or 360 for some commercial lenders)
Step 2: Track Daily Ending Balances
Daily Balance = Previous Balance + New Purchases - Payments/Credits
Step 3: Calculate Your Average Daily Balance (ADB)
ADB = (Sum of All Daily Balances in Billing Cycle) ÷ (Number of Days in Cycle)
Step 4: Calculate Total Monthly Interest Charge
Monthly Interest ($) = ADB × DPR × Number of Days in Billing Cycle
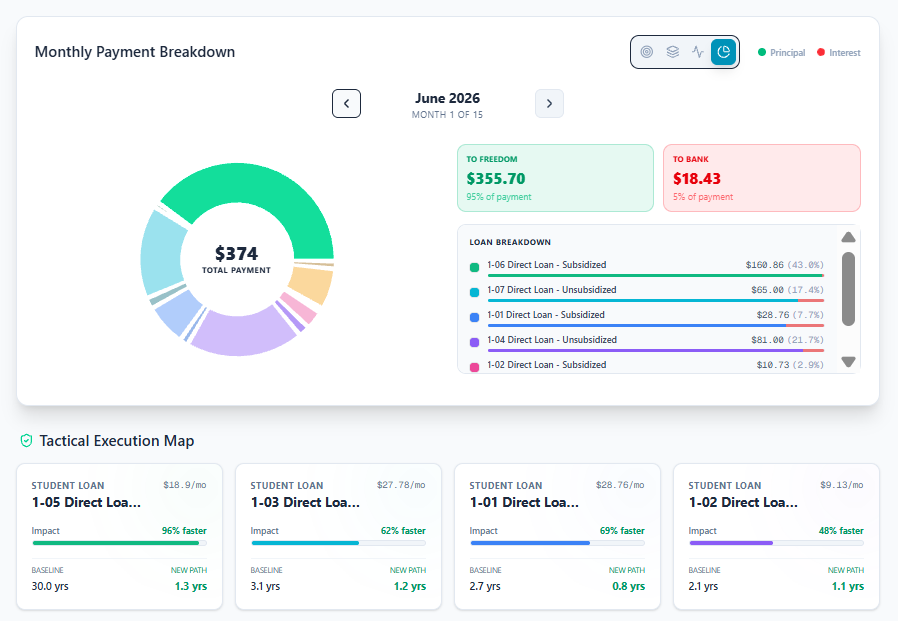
Figure 1: How the daily balance method quietly compounds finance charges throughout your billing cycle.
Real-World Example: The Timing Advantage
To see how the daily balance method affects your wallet in real time, compare two cardholders carrying a $10,000 balance at 24.99% APR during a 30-day billing cycle ($10k APR DPR = 0.06847% per day):
| Cardholder Scenario | Payment Amount & Timing | Average Daily Balance (ADB) | Monthly Interest Charge | Net Result |
|---|---|---|---|---|
| Borrower A (Waits for Due Date) | Pays $2,000 on Day 28 | $9,866.67 | $202.66 | Full interest charged for 28 days |
| Borrower B (Early Mid-Cycle Payment) | Pays $2,000 on Day 5 | $8,333.33 | $171.16 | Saves $31.50 in month 1 alone |
Both borrowers paid the exact same $2,000. But because Borrower B reduced their daily balance on Day 5, their Average Daily Balance dropped by over $1,533, instantly saving $31.50 in monthly interest. Compounded across a multi-year repayment schedule with a debt payoff calculator with extra payments, this single timing habit saves thousands of dollars.
Figure 2: Comparing payoff strategies that attack daily balance interest bleed at the root.
3 Rules to Outsmart the Daily Balance Method
1. Make Bi-Weekly or Mid-Month Payments
Instead of making a single monthly lump-sum payment on the due date, split your payment in half and pay every two weeks (or immediately after paydays). This keeps your daily balance lower throughout the cycle.
2. Beware of the “Trailing Interest” Trap
If you carry a balance and pay it off in full, you will often see a small interest charge on your next statement. That is trailing interest accrued under the daily balance method between your statement date and the day your payment posted.
3. Target Highest Dollar Bleed Accounts First
Because the daily balance method penalizes large balances heavily, deploying the Dynamic Blitz protocol to eliminate the card producing the largest daily dollar drain prevents explosive compounding (see when to apply dynamic strategies).
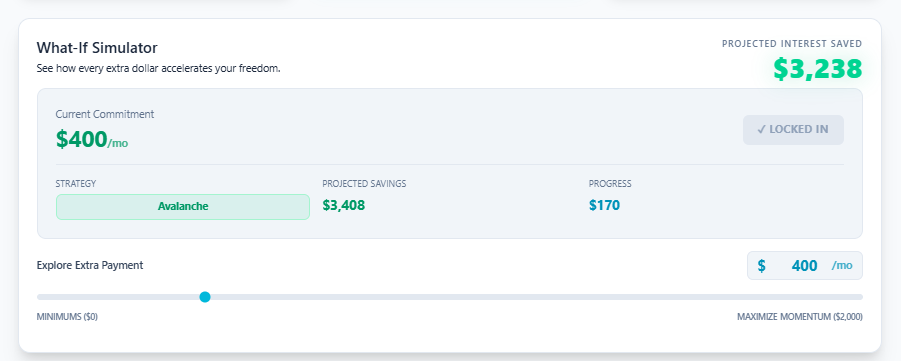
Figure 3: Simulating how extra payments suppress daily balance interest accrual in real time.
Frequently Asked Questions
What is the difference between Daily Balance and Average Daily Balance?
Do all credit card companies use the daily balance method?
How can I eliminate daily interest charges completely?
Interactive Daily Bleed Calculator
Stop letting the daily balance method drain your cash flow.
Calculate your exact daily interest velocity and map your fastest path to zero with LEVEL Debt-Free Architect. Run side-by-side strategy simulations, model what-if extra payments, and build an interactive 12-month construction blueprint—100% private, with zero bank sync required.