
Got a Lump Sum? Where to Put It When You Have Multiple Cards
Whether it is a $2,100 insurance payout, a seasonal bonus, an unexpected tax refund, or cash from selling unused property, receiving a sudden lump sum triggers an immediate dilemma: do you spread it evenly, dump it on the card with the ugliest interest rate, or completely eliminate small balances? Here is the mathematical decision framework lenders never teach you.
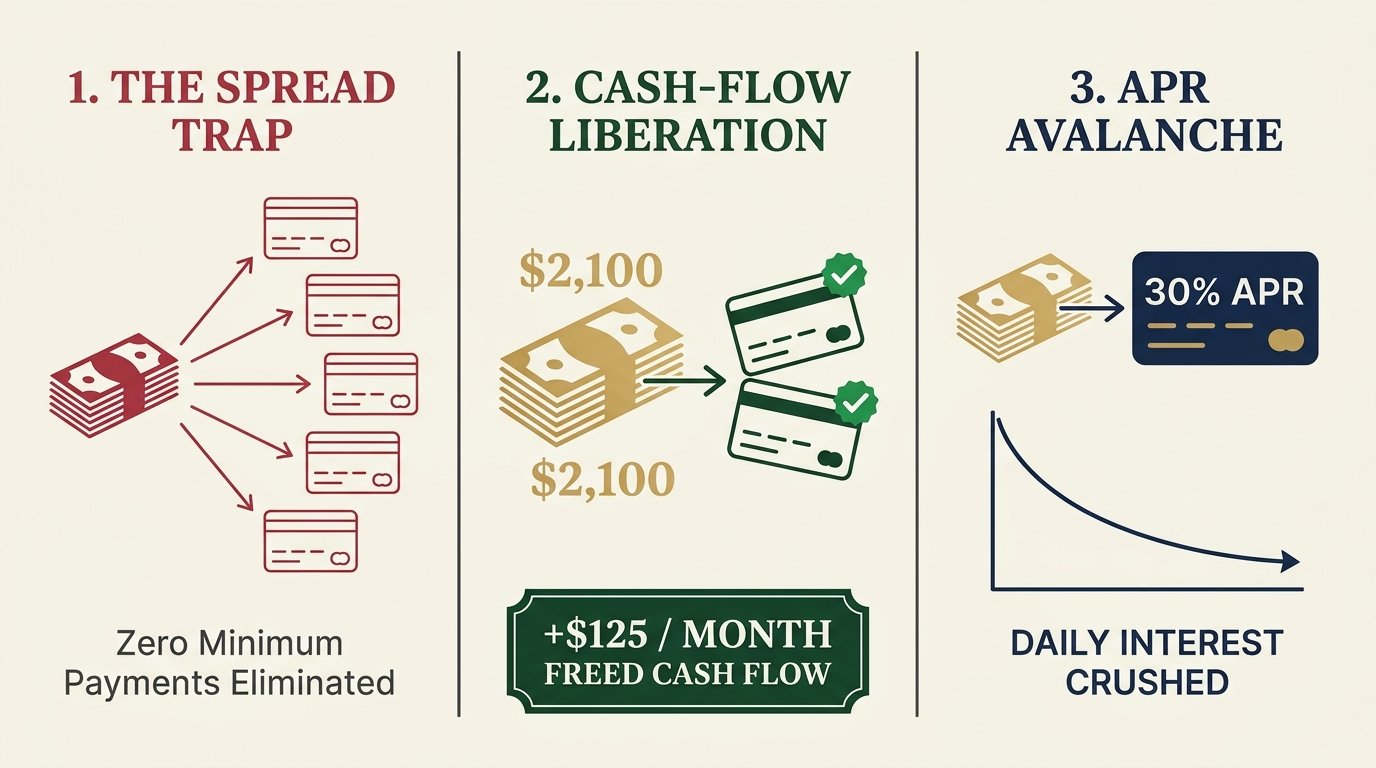
A borrower carries $10,500 in total revolving credit card debt scattered across five separate cards:
- Card A (Store Card): $650 balance · 31.99% APR · $35/mo minimum
- Card B (Retail Card): $1,150 balance · 28.99% APR · $50/mo minimum
- Card C (Gas Rewards): $1,800 balance · 24.99% APR · $60/mo minimum
- Card D (Main Travel Card): $3,100 balance · 21.99% APR · $85/mo minimum
- Card E (Primary Card): $3,800 balance · 19.99% APR · $95/mo minimum
Their total monthly minimum payments equal $325 every month just to keep the accounts current. After an insurance reimbursement clears, they have an unexpected $2,100 in cash sitting in their checking account.
Their first instinct is democratic: “Why don’t I send $420 to each of the five cards so every balance drops?” That instinct, while emotionally satisfying, is the single most expensive mistake a borrower can make.
The 100-Word Decision Rule: Cash-Flow Yield vs. APR Bleed
Never distribute a lump sum evenly across multiple credit cards. Chipping down five balances by a few hundred dollars leaves all five monthly minimum payments completely intact next month, providing zero relief to your monthly cash flow while compound daily interest continues chewing through your principal.
Instead, apply the Cash-Flow Yield vs. APR Bleed Rule: if your lump sum is large enough to completely eliminate one or two entire card balances, kill those accounts first (the Cash-Flow Strike). Wiping out balances destroys their required monthly minimum payments, immediately freeing up recurring cash flow that you roll into your remaining highest-APR balance. If your lump sum cannot zero out any single account, deploy 100% of it into your single highest-APR balance (the Avalanche Strike) to stop the maximum daily interest bleed.
Interactive Lump-Sum Debt Allocator
Test how your lump sum performs across different allocation strategies. Enter your windfall cash amount and your three most pressing card balances below:
The Three Competing Paths: Math Analyzed
Let us take the $2,100 real-world example from our opening case study and analyze what happens when that cash is deployed across the three major strategies.
| Deployment Strategy | Where the $2,100 Goes | Accounts Zeroed | Monthly Minimums Freed | Immediate Interest Impact |
|---|---|---|---|---|
| The Even Spread (The Trap) | $420 sent to each of the 5 cards | 0 Cards | $0.00 / month | Balances drop slightly, but you still must find $325 every month to make all 5 minimums. |
| The Cash-Flow Liberation Strike (Snowball) | $650 pays off Card A; $1,150 pays off Card B; remaining $300 hits Card C | 2 Cards ($0.00 Balance) | +$85.00 / month | Permanently eliminates two monthly payments ($35 + $50). Minimum burden drops from $325 to $240/mo. |
| The Pure APR Avalanche Strike | $2,100 deployed 100% against Card A (31.99% APR, balance $650) + Card B (28.99% APR, remainder) | 1 Card ($0.00 Balance) | +$35.00 / month | Eliminates the single most aggressive interest bleeds, saving over $58/month in ongoing compounding charges. |
Why “The Spread Trap” Keeps People in Debt
Spreading lump sums evenly is a classic psychological defense mechanism known in behavioral finance as mental naive diversification. You feel equitable, fair, and responsible because you touched every account.
In reality, lenders love when borrowers spread payments. When you send $420 to a $3,800 card, that account’s required minimum payment might decrease from $95 down to $87 next billing cycle—a meager $8 shift. Meanwhile, you still owe payments to five separate banks, you still face five separate due dates, and if an unexpected expense hits next month, you still need the full $300+ to avoid a 30-day late fee.
A debt is only neutralized when its minimum payment hits $0.00. Partial payments do not free up structural cash flow.
When evaluating which card to strike with a lump sum, calculate each card’s Cash-Flow Return on Capital:
Monthly Cash-Flow Return = (Required Monthly Minimum ÷ Payoff Balance) × 100
In our opening scenario, Card A requires $650 to eliminate a $35/month payment—a 5.38% monthly cash-flow return on your dollar ($35 ÷ $650). Card E requires $3,800 to eliminate a $95 payment—only a 2.50% return. Clearing Card A delivers over double the monthly breathing room per dollar spent.
When Should You Pick Cash Flow Over Highest APR?
Financial purists often argue that you should always target the highest APR first (the pure Avalanche method) because it mathematically minimizes total lifetime interest paid. While that is true on a spreadsheet, real humans do not live on spreadsheets.
You should choose the Cash-Flow Liberation Strike (killing smaller balances to wipe out minimums) when:
- Your Monthly Margin Is Razor Thin: If you are struggling to make ends meet each month, eliminating two $45 minimum payments puts $90 of real cash back into your checking account every single month. That $90 buffer acts as a shock absorber that prevents you from swiping a credit card when gas or groceries run short.
- You Are Preparing for a Loan or Mortgage: As explained in our guide to the Debt-to-Income (DTI) ratio calculator, mortgage and loan underwriters do not care how many dollars you owe in total balance—they care strictly about your required monthly minimum obligations. Wiping out two small cards eliminates their minimum payments completely, instantly improving your DTI ratio.
- You Suffer from Severe Financial Cognitive Overload: Managing five passwords, five due dates, and five statement cycles creates friction. Cutting five accounts down to three delivers immediate psychological momentum.
When Should You Pick Pure APR Avalanche?
Conversely, you should deploy 100% of your lump sum into the single highest-APR balance when:
- Your monthly cash flow is already stable and you have zero trouble covering all minimum payments out of your regular paycheck.
- The highest-APR card carries a punitive rate (such as a 32%–36% retail card) while your smaller cards sit at low promotional rates (e.g., 14%–18%).
- The lump sum is not large enough to completely wipe out any single card. If you have $500 and your smallest balance is $1,200, you cannot eliminate a minimum payment either way—so throw all $500 at the highest APR card to crush the daily interest bleed.
The Golden Rule: Never Spend Your Entire Buffer
Before sending every last penny of your lump sum to a card issuer, ask yourself one crucial question: Do you have at least $500 to $1,000 in liquid cash in a separate high-yield savings account?
As we detailed in our pillar guide on whether to build an emergency fund or pay off debt first, sending 100% of a windfall to a credit card company when your checking account has $50 left leaves you completely naked against life’s next flat tire or pharmacy bill. If an emergency strikes three days later, you will be forced to charge the card you just paid down—erasing your progress and demoralizing your momentum. Always carve out a basic cash cushion first, then deploy the rest as a laser strike.
Once you use a lump sum to wipe out Card A ($35/mo) and Card B ($50/mo), do not absorb that $85 back into your everyday dining or shopping budget. Add that exact $85 onto the minimum payment of your next target card (Card C). Because you were already accustomed to living without that $85, rolling it forward accelerates your remaining payoff velocity without feeling like a budget cut.
What About the Remaining Cards?
Once your lump sum is deployed and your smallest or highest-rate balances are zeroed, your remaining cards still carry high standard rates. Before continuing your monthly grind, take 30 minutes to review our playbook on how credit card hardship workout programs work. Calling your remaining card issuers and requesting an internal rate reduction can drop your remaining APRs down to single digits (6% to 9%), allowing your rolled-over monthly cash flow to destroy the remaining balances twice as fast.
Simulate Your Lump-Sum Strike with LEVEL
Don’t guess where your next windfall delivers the highest mathematical punch. Plug your balances into LEVEL to test one-time lump-sum strikes, compare Snowball cash-flow gains against Avalanche interest savings in real time, and lock in your permanent debt-free date. 100% private, no bank sync required.
Model Your Lump-Sum Strike Free →