Portfolio Engineering / Execution Blueprint
How to Pay Off $30,000 in Credit Card Debt: The Exact Sequence
Carrying $30,000 across multiple credit cards feels like trying to fill a bucket with a massive hole in the bottom. At 25% average APR, over $625 in pure interest vanishes every 30 days before touching a single cent of principal.
If you are searching for the fastest way to pay off $30,000 in credit card debt, conventional advice tells you to pick a single rigid formula: either the emotional momentum of the Snowball method or the mathematically optimal Avalanche method.
However, when managing a real $30k multi-card portfolio with divergent APRs and variable cash flow, you need an exact mathematical sequence. By calculating your daily dollar bleed (as explored in how to calculate your daily interest bleed) and using a debt payoff calculator with extra payments, you can eliminate $30,000 in under 24 months without taking out risky consolidation loans.
The $30k Portfolio Breakdown: Where the Money Goes
Consider a representative $30,000 debt portfolio split across three common credit card accounts:
- Card A (Store Card): $4,500 balance @ 29.99% APR ($135 min payment | $3.70/day bleed)
- Card B (Primary Visa): $17,500 balance @ 24.99% APR ($440 min payment | $11.98/day bleed)
- Card C (Travel Card): $8,000 balance @ 21.99% APR ($200 min payment | $4.82/day bleed)
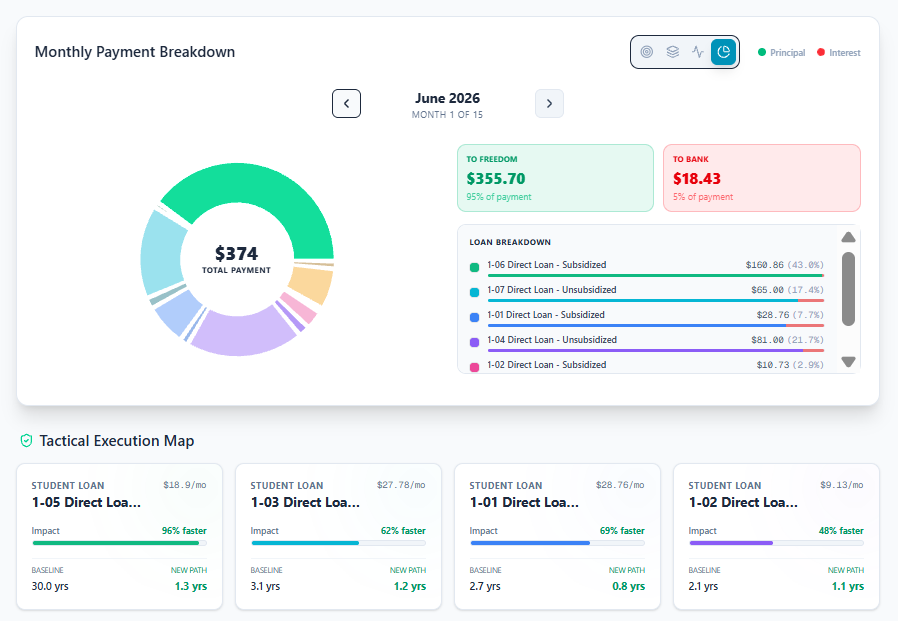
Figure 1: Visualizing how daily interest consumes minimum payments before reducing the $30k principal balance.
The 4 Repayment Scenarios: Minimums vs. Dynamic Blitz
Here is how different repayment strategies perform when tackling this $30,000 balance:
| Strategy | Monthly Payment | Debt-Free Timeline | Total Interest Paid | Total Financial Savings |
|---|---|---|---|---|
| 1. Minimums Only (The Trap) | $775 (Decreases) | 23.8 Years | $24,850 | $0 (Baseline) |
| 2. Fixed Minimum Floor ($800/mo) | $800 / month | 5.2 Years | $12,400 | Save $12,450 & 18.6 Yrs |
| 3. Snowball + Extra ($1,400/mo) | $1,400 / month | 2.3 Years (28 mos) | $5,820 | Save $19,030 & 21.5 Yrs |
| 4. Dynamic Blitz + Extra ($1,400/mo) | $1,400 / month | 2.1 Years (25 mos) | $4,940 | Save $19,910 & 21.7 Yrs |
By moving from minimums (see how to escape the minimum payment trap) to a targeted $1,400/month allocation using the Blitz Protocol, you shave 21.7 years off your timeline and save nearly $20,000 in cash.
Figure 2: Comparing multi-strategy allocation to eliminate $30,000 in debt with mathematical precision.
The 4-Step Sequence to Eliminate $30k in Under 24 Months
Phase 1: Kill the Highest Daily Dollar Bleeder
Maintain contractual minimums on Card A and Card C, but funnel 100% of your extra cash flow into Card B ($17,500 @ 24.99%). Card B generates 58% of your total daily dollar drain ($11.98/day). Halving Card B immediately relieves cash flow pressure.
Phase 2: Eliminate the Toxic Rate Card
Once Card B’s daily bleed drops below Card A, pivot extra cash flow to extinguish Card A ($4,500 @ 29.99% APR) in under 4 months. Eliminating Card A permanently closes one account and frees its $135 minimum payment.
Phase 3: The Cascading Avalanche Roll
Roll the freed $135 minimum into your extra payment pool, raising your monthly attack vector to $1,535/mo. Annihilate the remainder of Card B, then roll all cash into finishing Card C ($8,000).
Phase 4: Track Your 12-Month Milestone Construction
Review your numbers for 5 minutes each month. Watching your debt-free milestone bricks turn green eliminates ambiguity and reinforces discipline.
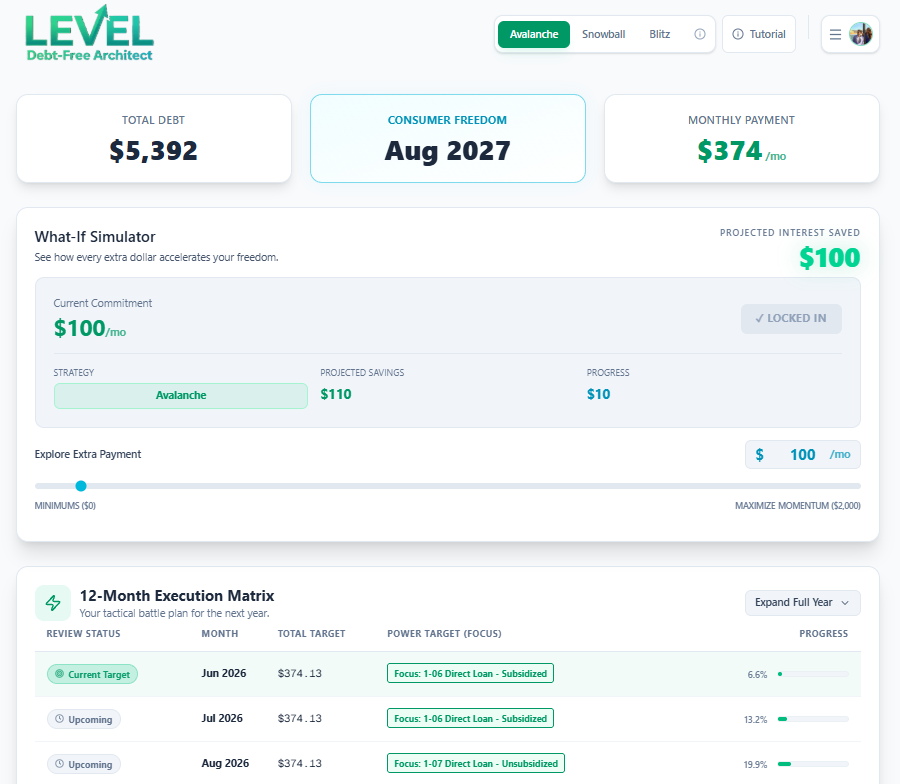
Figure 3: Interactive 12-month construction blueprint tracking dynamic progress to zero debt.
Frequently Asked Questions
Should I take out a $30,000 personal consolidation loan?
How much extra money do I need each month to pay off $30k in 2 years?
Can balance transfer cards help with $30,000 in debt?
Interactive $30k Payoff Blueprint
Stop guessing your timeline. Map your exact path to zero debt.
Simulate your custom $30k payoff plan today with LEVEL Debt-Free Architect. Compare Snowball, Avalanche, and Dynamic Blitz strategies side by side, test extra payment injections, and build your visual 12-month construction blueprint—100% private, with zero bank sync required.