Promotional Windows / Interest Mitigation
The 0% Promo Cliff: What Happens When Deferred Interest Expires
0% promotional financing feels like free money until the clock runs out. If you carry a balance on a 0% introductory card, balance transfer, or store financing plan, falling off the promotional cliff can trigger hundreds—or thousands—in unexpected retroactive interest charges.
Thousands of borrowers search every month asking: what happens when 0 percent credit card promo expires? The answer depends entirely on the fine print of your credit agreement: whether your card features a true 0% introductory APR or a predatory deferred interest clause.
Understanding this distinction—and learning how to calculate your daily interest bleed before the deadline hits (as explored in how to calculate your daily interest bleed)—is the difference between saving money and getting trapped in a multi-thousand-dollar interest penalty.
True 0% Intro APR vs. Deferred Interest: The Critical Difference
Card issuers use two completely different mechanisms when offering 0% promotional rates:
Type 01: True 0% Intro APR
Standard Bank Balance Transfers
Offered by major issuers (Chase, Citi, Discover). When the 0% period ends, the standard variable APR (e.g., 24.99%) applies only to the remaining balance moving forward. No retroactive interest is assessed.
Type 02: Deferred Interest Trap
“No Interest If Paid in Full”
Common with store credit cards, PayPal Credit, CareCredit, and furniture financing. If the balance is not 100% paid off to $0.00 by the promo date, interest is retroactively calculated on the entire original purchase amount from Day 1.
The Deferred Interest Calculation Bomb
The $50 Leftover Balance Trap
Imagine purchasing $4,000 of furniture with a “12 Months No Interest If Paid in Full” promotion at 29.99% APR.
Over 12 months, you diligently pay down $3,950, leaving just $50 unpaid on Day 366.
Under deferred interest terms, the lender does not charge interest on $50. They retroactively calculate 29.99% APR on the entire $4,000 balance for the full 365 days—instantly adding $1,199.60 in retroactive interest to your account on Month 13!
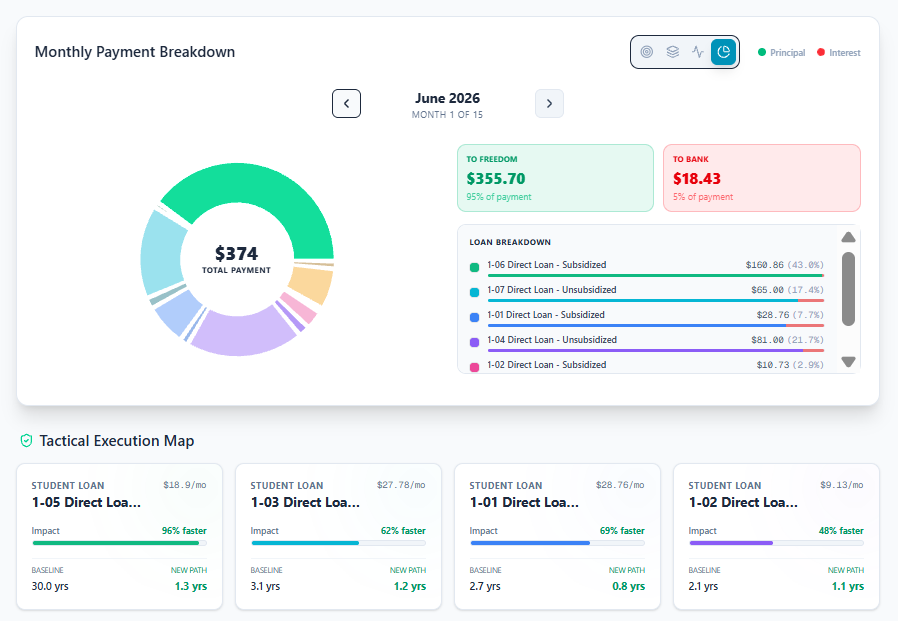
Figure 1: Visualizing how monthly interest explodes the moment a 0% promotional window expires.
Why Minimum Payments Guarantee You Will Fall Off the Cliff
The single biggest reason cardholders get stung by expiring 0% promos is trusting the card issuer’s monthly statement minimum payment (see the minimum payment trap).
Federal regulations do not require card issuers to set minimum monthly payments high enough to pay off promotional balances before the expiration date. In fact, most store cards calculate minimum payments at 1% to 2% of the balance—guaranteeing that 35% to 50% of the principal remains unpaid when the promo expires!
| Promo Scenario ($5,000 @ 0% for 12 Mos) | Monthly Payment | Remaining Balance at Mo 12 | Retroactive Interest (28.99%) | Total Cost |
|---|---|---|---|---|
| 1. Paying Minimums Only | $100 / month | $3,800 Unpaid | +$1,449.50 (Penalty) | $6,449.50 |
| 2. Equal Installments ($5k ÷ 12) | $416.67 / month | $0.00 (Zero) | $0.00 (Avoided) | $5,000.00 |
| 3. 30-Day Buffer Payoff ($5k ÷ 11) | $454.55 / month | $0.00 (Paid at Mo 11) | $0.00 (Safe) | $5,000.00 |
Figure 2: Strategically prioritizing expiring promotional balances alongside high-APR revolving cards.
The 4-Step Action Plan to Defuse an Expiring 0% Card
1. Identify the Exact Promotional Cutoff Date
Do not rely on your monthly statement due date. Check the “Promotional Summary” section at the bottom of your statement for the exact expiration date (often mid-billing cycle).
2. Build a 30-Day Payoff Buffer
Divide your remaining balance by the number of months remaining minus one. If you have 6 months left on a $3,000 balance, budget $600/month ($3,000 ÷ 5) to eliminate the balance 30 days before the promo expires. This protects against bank processing delays or disputed charges.
3. Use Dynamic Blitz Priority for Deferred Cards
Even though a 0% deferred interest card shows a current rate of 0%, its effective future interest bleed is massive. Using a debt payoff calculator with extra payments, route surplus cash to eliminate deferred balances 60 days before the deadline (as detailed in when to apply dynamic strategies).
4. Consider a Secondary Balance Transfer (If Time is Short)
If you cannot clear the balance before the promo cliff, transfer the remaining chunk to a true 0% bank card (see balance transfers vs consolidation loans) to avoid paying 30% retroactive interest.
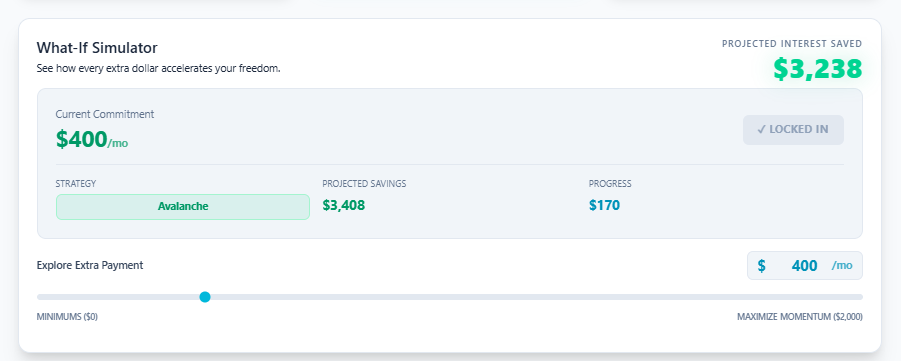
Figure 3: Simulating surplus cash flow routing to extinguish promotional debt before the expiration cliff.
Frequently Asked Questions
How can I tell if my card has deferred interest or true 0% APR?
What happens if I make a late payment during a 0% promo period?
Where do payments go if I have both a 0% promo and a standard balance?
Interactive Promotional Payoff Simulator
Defuse your promotional cards before the deadline hits.
Model your exact repayment timeline today with LEVEL Debt-Free Architect. Simulate extra payment injections, track your visual 12-month construction roadmap, and eliminate expiring promo balances with zero bank sync required.