
Does Paying Off Debt Raise Your Credit Score? The Timeline, Traps & Exact Math
Few moments in personal finance feel more triumphant than submitting a final, balance-clearing payment to a credit card issuer or loan servicer. You imagine the credit reporting agencies sounding a brass fanfare as your score catapults into the pristine 800s.
Then, four weeks later, you check your credit monitoring app and stare in disbelief: your credit score dropped 18 points.
Did you break something? Is the credit reporting system actively punishing you for fiscal responsibility?
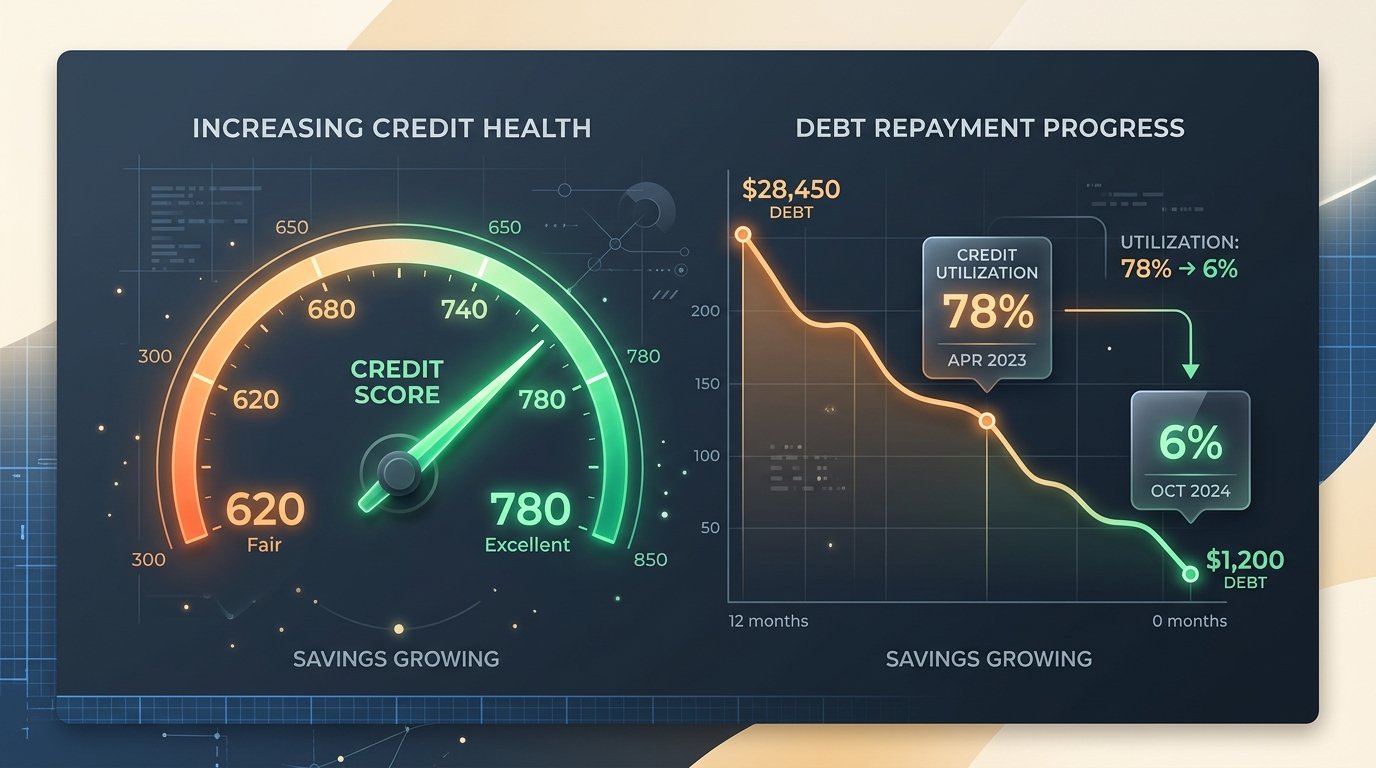
The short answer is: Yes, paying off debt raises your credit score over the long term—often dramatically. However, the short-term mechanics of FICO® and VantageScore® algorithms contain counterintuitive rules. Understanding the difference between revolving debt and installment debt, credit utilization thresholds, and reporting lag is the difference between panic and mathematical clarity.
1. Revolving vs. Installment Debt: The Fundamental Divide
Credit scoring algorithms do not treat all liabilities equally. To understand how payoff impacts your score, you must immediately categorize your balance into one of two buckets:
- Revolving Credit: Credit cards, store cards, and Home Equity Lines of Credit (HELOCs). These accounts have an approved credit ceiling that you can repeatedly borrow against, repay, and borrow against again.
- Installment Loans: Auto loans, mortgages, student loans, and fixed-term personal loans. You borrow a lump sum upfront and repay it in equal monthly installments over a predetermined horizon.
| Scoring Factor | Paying Off Revolving Debt (Credit Cards) | Paying Off Installment Debt (Auto/Student) |
|---|---|---|
| Immediate Score Impact | Significant Increase (+20 to +80 pts) | Neutral, Minor Gain, or Temporary Dip (-5 to -25 pts) |
| Primary Algorithm Lever | Credit Utilization Ratio (30% of FICO) | Credit Mix (10%) & Active Account Diversity |
| Reaction Speed | Next statement closing cycle (30 days) | 30 to 60 days following account closure |
| Account Status Post-Payoff | Account stays open with $0 balance & full limit | Account closes permanently |
| Long-Term Net Effect | Transformative score optimization | Solid positive payment history remains for 10 years |
When you pay down a $10,000 credit card balance to $0, the credit line remains open. Your total borrowing capacity stays intact, but your used balance collapses. This directly slashes your credit utilization ratio, triggering rapid score increases.
Conversely, when you make the 60th and final payment on an auto loan or personal loan, the lender closes the account. While you are officially free of monthly payments, your credit report now has one less active account demonstrating on-time monthly performance.
2. The Mathematics of Credit Utilization: FICO’s 30% Weight
Under the FICO® scoring model, Amounts Owed accounts for roughly 30% of your total score (approximately 165 out of 550 possible variable points). The centerpiece of this category is your credit utilization ratio.
Calculated both on an aggregate portfolio basis (all cards combined) and an individual card basis (the highest balance on any single line).
Many consumers mistakenly believe that credit utilization is a binary switch: below 30% is good, above 30% is bad. In reality, credit scoring algorithms assess utilization in tiered non-linear brackets:
- Maxed-Out Bracket (70% – 100%+): Severe scoring penalty. Algorithms flag the consumer as high risk for impending default.
- Elevated Bracket (30% – 69%): Noticeable point suppression. Even if you make every minimum payment on time, carrying 45% utilization can easily suppress your score by 40 to 60 points.
- Healthy Bracket (10% – 29%): The conventional standard. Avoids severe penalties, but leaves substantial points on the table.
- Elite Bracket (1% – 9%): The sweet spot for top-tier FICO scores (780 to 850). Demonstrates active credit management with near-zero balance risk.
- The 0% Trap (All Zero Across Every Card): Counterintuitively, reporting exactly $0 across every single revolving card can result in a minor 10-to-15 point suppression compared to reporting a 1% utilization. Scoring models evaluate active usage; having 100% idle accounts provides no recent data to score.
The Per-Card Utilization Trap
Aggregate utilization is not enough. If you have $40,000 in total credit limits across four cards, and carry a $9,000 balance on Card A (limit $10,000) while Cards B, C, and D sit at $0: your aggregate utilization is 22.5% (healthy). However, FICO will penalize you heavily because Card A sits at 90% utilization. To maximize score recovery, balances must be smoothed down across individual lines.
3. Why Did My Score Drop After Paying Off Debt? (The 4 Culprits)
If you recently paid off a balance and your credit score tumbled, do not panic. This is one of the most common surprises in personal finance. Here are the four structural reasons why it occurs:
Culprit #1: You Closed the Credit Card Account
After paying off a frustrating high-APR card, your emotional impulse is often to cut up the card and call the issuer to close the account permanently.
The mathematical consequence: Closing a card with a $5,000 limit instantly deletes $5,000 of available credit from your denominator. If you carry balances on other cards, your overall utilization spikes overnight, driving your score down.
Culprit #2: You Paid Off Your Only Installment Loan
FICO’s Credit Mix accounts for 10% of your score. Lenders favor borrowers who demonstrate competence managing a diverse spectrum of debt (revolving cards alongside structured installment loans).
When you pay off your only open auto loan, student loan, or mortgage, your active credit mix shrinks to zero installment lines. The closed loan remains on your report for up to 10 years as positive historical data, but the loss of an active installment trade line can cause an immediate 10-to-25 point dip.
Culprit #3: Statement Closing Dates vs. Due Dates
Credit bureaus do not receive live transaction telemetry from banks. Lenders report your balance to Experian, Equifax, and TransUnion once a month—typically on your statement closing date, NOT your payment due date.
If your statement closes on the 12th with a $3,000 balance, and you pay it in full on the 18th: the credit bureaus still see a $3,000 balance until the next statement cycle generates on the 12th of the following month. For up to 30 days, your score reflects the old debt.
Culprit #4: VantageScore vs. FICO Scoring Models
Free credit monitoring apps (like Credit Karma) almost universally display VantageScore 3.0, whereas 90% of top mortgage, auto, and commercial lending institutions evaluate FICO Score 8, 9, or 10.
VantageScore is notoriously volatile regarding closed installment accounts. A student loan payoff can cause a 30-point plunge on VantageScore, while your actual FICO score remains virtually unchanged or moves upward.
4. The Month-by-Month Score Trajectory
When executing a deliberate payoff sequence like Debt Snowball, Debt Avalanche, or Dynamic Blitz, here is the realistic timeline of how your credit profile responds:
- Month 1 (Initiation): You begin directing concentrated cash flow to target balances. Total debt drops by $1,000–$2,000. Score impact is muted (+5 to +10 pts) as balances cross minor percentage brackets.
- Months 2–4 (The Utilization Breakthrough): As revolving balances drop below 50% and then below 30%, you hit the steepest curve of the algorithm. Scores frequently jump 25 to 55 points during this phase.
- Months 5–8 (The Account Zero Phase): Individual credit cards hit zero balances. If you keep the lines open, your available credit cushion expands dramatically. Scores stabilize in the mid-700s.
- Month 12+ (The Clean Finish): Debt-free status reached on revolving lines. Your score settles into the 780–820 range, with lower insurance premiums, pre-approved Tier-1 lending rates, and maximum financial flexibility.
5. How to Pay Off Debt to Maximize Credit Score (Action Blueprint)
If your goal is to optimize your credit score while eradicating debt, follow these four foundational rules:
- Keep Paid-Off Cards Open: Resist the urge to close zero-balance accounts. Keep the account active by putting a small recurring $5 subscription (such as iCloud or Spotify) on autopay, paired with automated full statement balance payoffs. This preserves your total credit limit and account age.
- Pay Down Cards Before the Statement Date: Find the “Statement Closing Date” on your monthly bill (usually 21–25 days before your payment due date). Pay down balances 3 days before this statement cuts. The bank will report a near-zero balance to the credit bureaus.
- Target High-Utilization Cards First: If optimizing for a near-term mortgage or auto loan application within 90 days, bringing cards that are over 70% down under 30% generates the fastest credit point surge.
- Kill Daily Interest Bleed Above All Else: Never let credit score micromanagement distract you from cold mathematical reality. A 10-point temporary score dip does not cost you money; paying 28% APR on revolving balances costs you cold, hard cash every single morning.
Stop Managing Minimums. Engineer Your Finish Line.
Your credit score is an automatic byproduct of sound financial architecture—not the goal itself. Use LEVEL’s 100% private, zero-bank-sync payoff simulator to visualize your exact debt-free date, model extra payments, and eliminate daily interest bleed brick by brick.
Calculate Your Payoff Date at DebtFreeArchitect.com