Best Debt Payoff Apps in 2026 (Without Bank Linking): LEVEL vs. Undebt.it vs. Atlas vs. YNAB
The best debt payoff app in 2026 that does not require linking your bank account is LEVEL (for borrowers who want a deterministic Dual-Engine planner comparing Debt Avalanche, Debt Snowball, and Daily Interest Bleed side by side), followed by Undebt.it (for desktop spreadsheet tinkerers), Atlas (for mobile-only users who strictly want the Debt Snowball method with an AI chatbot), and YNAB (for full zero-based expense tracking). Choosing the wrong payoff architecture—especially locking yourself into a Snowball-only app when you carry 28% APR credit cards—can quietly cost you over $3,100 in avoidable interest.
A borrower carries $22,000 in debt across four accounts: a $1,200 retail card at 0% promotional APR, a $2,800 personal loan at 11% APR, a $6,500 credit card at 24.99% APR, and an $11,500 credit card at a punishing 28.99% APR. Unwilling to hand over their raw bank login passwords to third-party data aggregators, they download a popular mobile debt snowball app.
Because that app is hard-coded exclusively around the Debt Snowball method (smallest balance first), it instructs them to direct all $400 of their monthly extra cash into the $1,200 0% retail card and the 11% personal loan first—leaving the $11,500 balance at 28.99% APR untouched for 11 months. During those 11 months, that single 28.99% card bleeds $9.13 every single day in compound finance charges.
When they plug the exact same four accounts into LEVEL, the deterministic engine reveals the truth in two seconds: switching from a blind Snowball sequence to a targeted Avalanche blitz cuts their total interest by $3,140 and gets them out of debt 7 months sooner on the exact same monthly budget.
Why Borrowers Are Rejecting Bank-Syncing Apps in 2026
For years, mainstream personal finance apps demanded the same price of admission: hand over your bank username, password, and multi-factor authentication tokens to a third-party data aggregator (such as Plaid, Finicity, or MX). In return, the app scraped every coffee purchase, paycheck deposit, and medical transaction you made.
After automated debt apps like Tally abruptly shut down—as we documented in our deep dive on why zero-bank-sync architecture beats automated middleman apps—borrowers realized two critical truths:
- You Do Not Need Transaction Scraping to Pay Off Debt: Paying off debt requires only four numbers per account: your current balance, your APR, your minimum payment rule, and your monthly surplus cash flow.
- “No Bank Linking” Does Not Always Mean Private: A new wave of mobile apps advertise “no bank linking,” yet require you to sign an AI Data Consent Waiver because their built-in “AI Financial Coach” transmits your financial prompts and debt numbers to third-party Large Language Model (LLM) servers. True privacy means neither bank credential scraping nor third-party AI training waivers.
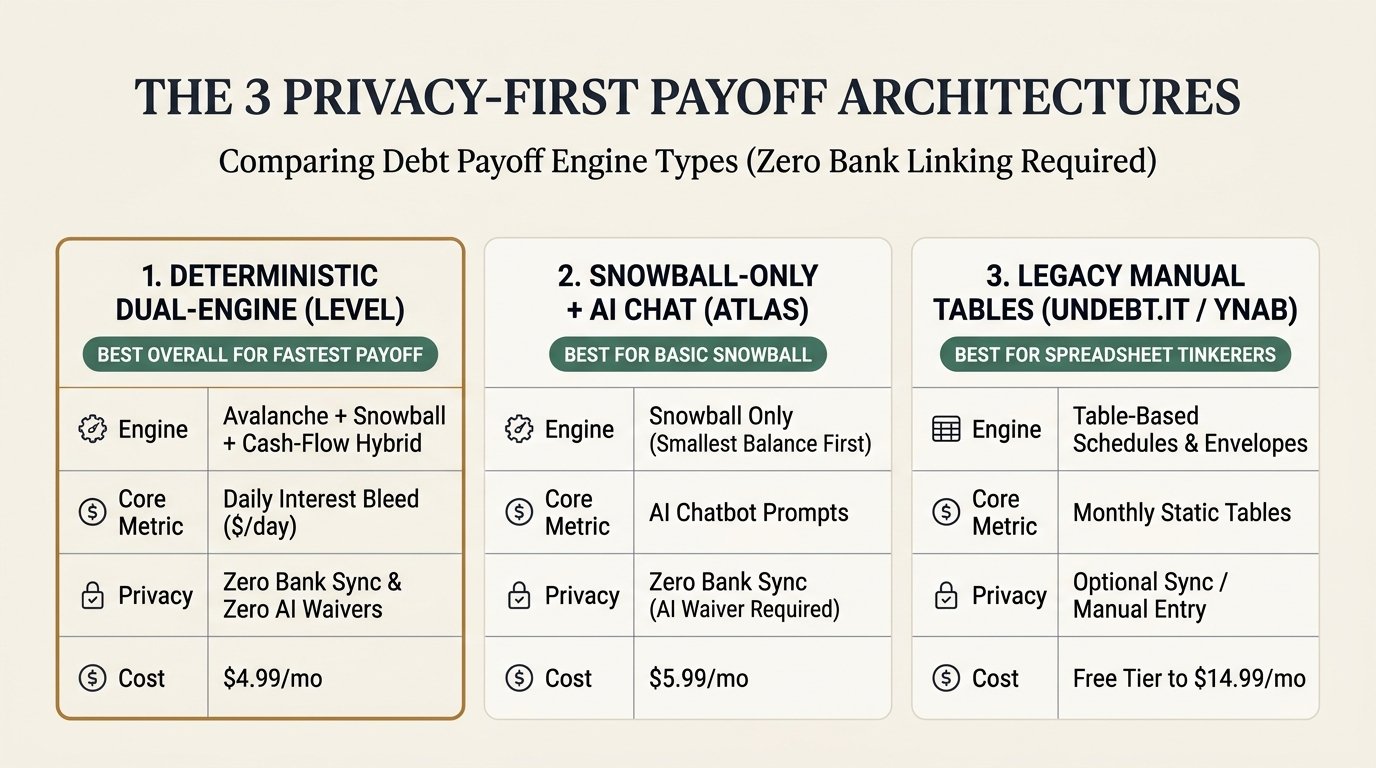
| Platform | Payoff Math Engine | Bank Sync Required? | Third-Party AI Data Waiver? | Best For | Pricing (2026) |
|---|---|---|---|---|---|
| 1. LEVEL (debtfreearchitect.com) |
Dual-Engine Deterministic (Avalanche, Snowball, Cash-Flow Yield & Daily Interest Bleed) | Never (100% Zero-Sync) | None (Pure deterministic math, zero LLM data sharing) | Fastest mathematical payoff & instant What-If scenario modeling | $4.99 / mo (Early-adopter tier; instant web & mobile) |
| 2. Undebt.it | Table-based Snowball, Avalanche & Custom Order | No (Manual entry) | Optional (Waitlist/AI add-ons) | Desktop power users who love dense multi-tab amortization tables | Free base tier; $12 / year premium |
| 3. Atlas Budget | Snowball-Only (Smallest balance first) | No (Manual entry) | Yes (Requires `/ai-consent` for AI Coach) | Mobile users who strictly want Dave Ramsey-style Snowball + AI chat | $5.99 / mo or $59.99 / yr (after 7-day trial) |
| 4. YNAB (You Need A Budget) |
Zero-Based Envelope Budgeting (Basic loan payoff simulator) | Optional (Built for Plaid sync, allows manual) | None | Hands-on daily expense tracking & envelope budgeting | $14.99 / mo or $109 / yr |
| 5. EveryDollar | Snowball-Only (Baby Steps framework) | Free tier is manual; Premium links banks | None | Strict followers of the 7 Baby Steps methodology | Free basic; $17.99 / mo or $79.99 / yr |
1. LEVEL — Best Overall for Fastest Payoff & True Zero-Knowledge Privacy
LEVEL was engineered around a single uncompromising premise: when you are carrying high-interest revolving debt, every day is a mathematical race against compound interest. You do not need a bloated expense tracker shaming you over a $5 coffee, nor do you need a generic AI chatbot giving you pep talks. You need an architectural blueprint that shows you the fastest path to $0.
Where LEVEL Wins:
- Exposes Your Exact Daily Interest Bleed: Most borrowers have no idea what their APR actually costs them each day. LEVEL calculates your real-time Daily Interest Bleed (Daily Interest = [Balance × APR] ÷ 365) on every card and across your entire portfolio, showing you down to the penny how much money vanishes between breakfast and dinner.
- Avalanche vs. Snowball vs. Hybrid in One Click: Instead of forcing you into a single dogma, LEVEL’s Dynamic Blitz Engine lets you toggle instantly between the Debt Avalanche (highest APR first for maximum dollar savings) and the Debt Snowball (smallest balance first for rapid account closures and minimum-payment cash-flow yield).
- Instant “What-If” Scenario Simulator: Want to see how a 6% credit card hardship program, a 7.5% nonprofit Debt Management Plan, or an extra $150/month from a side gig shifts your exact debt-free month? LEVEL models it live in your browser without touching your underlying records.
- 100% Private (Zero Bank Sync + Zero AI Waivers): LEVEL never asks for your banking credentials, never runs a credit pull, and never ships your financial balances to third-party LLM servers.
Pricing: $4.99/month (early-adopter rate for the first 100 subscribers; runs instantly on any mobile phone, tablet, or desktop browser with zero App Store lock-in).
2. Undebt.it — Best Legacy Tool for Desktop Spreadsheet Tinkerers
Undebt.it is one of the longest-running independent web tools in the debt payoff space. Built years before modern mobile fintech apps existed, it functions like a supercharged online spreadsheet with dozens of configuration toggles.
Where Undebt.it Wins:
- Generous Free Tier: Its core payoff table generator—including Snowball, Avalanche, and custom ordering—is available free of charge without linking a bank account.
- Granular Account Toggles: Users who enjoy configuring bi-weekly payment schedules, promotional rate expiration dates, and printable HTML tables on a desktop monitor will appreciate its depth.
The Trade-Offs:
Undebt.it’s interface feels distinctly like a 2014 accounting database. On a smartphone screen, navigating dense multi-column amortization tables can feel overwhelming for borrowers who want a clean visual roadmap and instant clarity on their daily interest burn.
3. Atlas Budget — Best for Mobile Users Who Strictly Want Snowball + AI Chat
Atlas Budget (`atlas-budget.com`) is a mobile application for iOS and Android that pairs manual expense budgeting with a Debt Snowball planner and a conversational AI coach.
Where Atlas Wins:
- Clean Mobile Interface & No Bank Linking: Like LEVEL and Undebt.it, Atlas does not require Plaid bank connections or credit checks to build a payoff timeline.
- Conversational AI Assistant: For users who prefer typing questions into a chat interface (e.g., asking the bot how to categorize an expense or which small bill to tackle first), the built-in AI coach provides plain-English replies.
The Trade-Offs:
- Locked Into the Debt Snowball: Atlas is built specifically around the Debt Snowball method (ordering debts strictly from smallest balance to largest balance). If you carry a $12,000 balance at 29% APR and three smaller balances at 8%–12%, a Snowball-only schedule leaves your 29% card compounding at full force for months or years—costing thousands in avoidable interest.
- Third-Party AI Data Consent: Because Atlas relies on an LLM-powered AI coach, users must agree to a separate AI consent policy governing how chat inputs and financial context are processed by AI providers.
- Higher Monthly Cost: Priced at $5.99/month ($59.99/year) after a 7-day trial, and requires downloading a native mobile app.
Consider a household with $19,500 in total debt and $850/month total payment capacity ($490 required minimums + $360 extra blitz cash):
- Account A (Medical Payment Plan): $1,500 balance at 0% APR ($75/mo minimum)
- Account B (Auto Loan Balance): $3,500 balance at 6.5% APR ($115/mo minimum)
- Account C (Revolving Card 1): $5,500 balance at 24.99% APR ($120/mo minimum)
- Account D (Revolving Card 2): $9,000 balance at 28.99% APR ($180/mo minimum)
Result Under Snowball-Only (Smallest Balance First): You spend the first 11 months paying off the 0% medical bill and the 6.5% car loan while Cards C and D charge $10.91 per day ($331/month) in high-APR interest. Total interest paid: $6,480. Time to debt-free: 31 months.
Result Under LEVEL’s Avalanche Blitz (Highest APR Bleed First): You attack the 28.99% card on Day 1 while keeping the 0% medical bill at its bare minimum. Total interest paid drops to $3,890, and you reach $0 in 27.5 months—saving $2,590 in cold cash without paying a single dollar more per month.
4. YNAB (You Need A Budget) — Best for Zero-Based Expense Envelope Tracking
YNAB is the gold standard for zero-based envelope budgeting (“give every dollar a job”), helping households control day-to-day discretionary spending.
Where YNAB Wins:
- Behavioral Spending Control: If your core problem is not knowing where your paycheck goes each month, YNAB’s four rules force you to allocate cash into categories before you spend it.
- Can Be Used Without Bank Sync: Although YNAB heavily promotes automated bank importing, you can toggle any account to “Unlinked” and enter transactions manually.
The Trade-Offs:
YNAB is a budgeting method, not a dedicated multi-debt optimization engine. It does not automatically sequence seven different credit cards by Avalanche vs. Snowball cash-flow yield, and at $14.99/month ($109/year), it is three times the cost of LEVEL—steep when you are trying to direct every spare dollar toward principal reduction.
If you have no idea how much you spend on groceries and dining out each month, start by auditing your last 60 days of bank statements. Once you know your monthly surplus number—whether that is $150 or $1,000—a dedicated payoff architect like LEVEL is what turns that surplus into the shortest possible mathematical timeline to zero debt.
Test Your Exact Payoff Architecture With LEVEL
See what your debt-free date looks like under a targeted Avalanche strike vs. a Debt Snowball in less than two minutes. LEVEL exposes your exact Daily Interest Bleed down to the cent, models 12-month visual blueprints, and keeps your financial data 100% private—zero bank logins and zero AI data waivers required.
Launch LEVEL Free in Your Browser →