Debt Snowball vs. Debt Avalanche Calculator: See Your Exact Payoff Difference
The Debt Avalanche method (paying off your highest interest rate first) almost always saves you significantly more money and finishes months earlier than the Debt Snowball method (paying off your smallest balance first)—especially when credit card APRs sit between 24% and 29.99%. However, the Debt Snowball unlocks recurring monthly cash flow faster by eliminating individual minimum payments early. Use our free, no-signup multi-account calculator below to see your exact dollar and timeline difference in real time.
Interactive Debt Snowball vs. Avalanche Calculator (Free, No Signup)
Unlike single-method calculators that only show you the Debt Snowball, our dual-engine simulator below runs both amortization algorithms simultaneously across four accounts. Adjust the balances, APRs, minimum payments, and your monthly extra payment to see your exact interest savings, payoff timeline, and Month 1 Daily Interest Bleed:
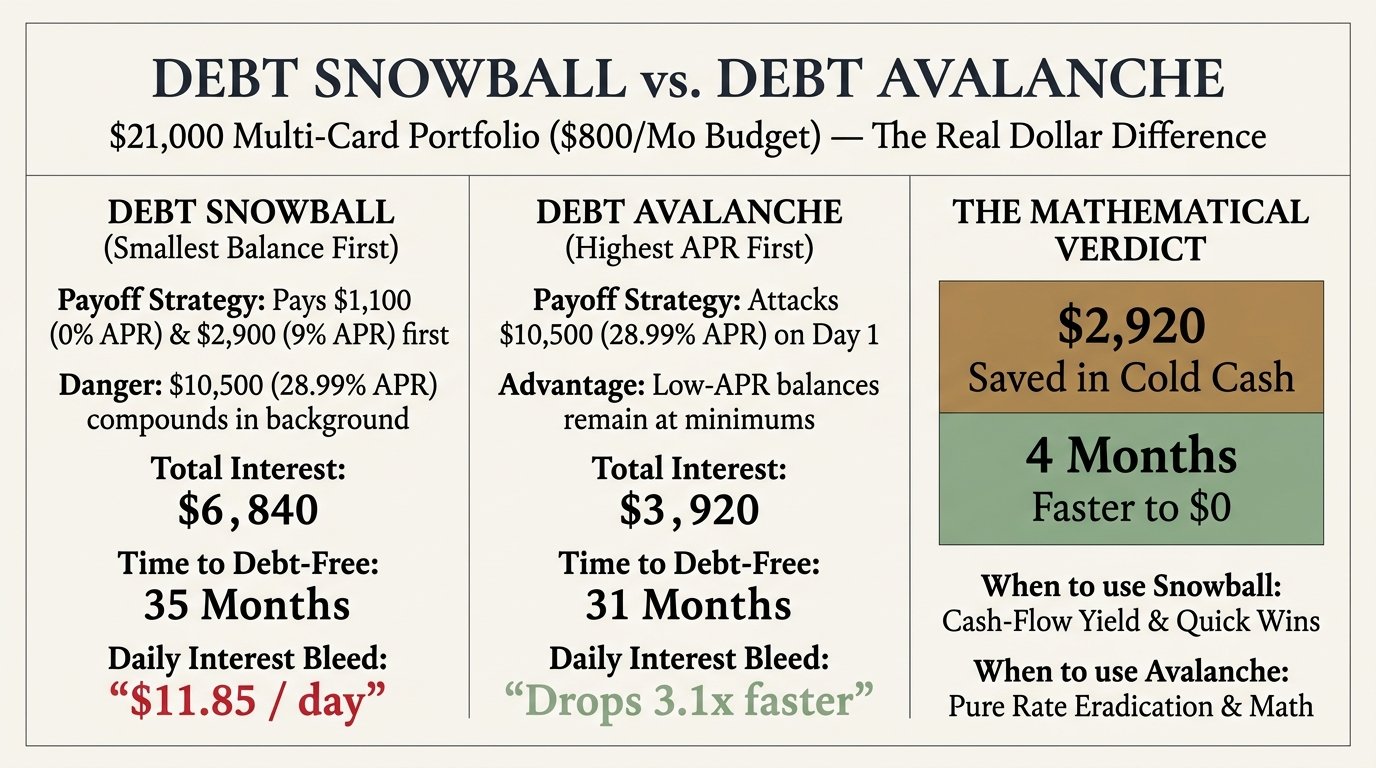
A household carries $21,000 in total debt across four accounts: a $1,100 medical payment plan at 0% APR ($55/mo minimum), a $2,900 credit union personal loan at 9% APR ($85/mo minimum), a $6,500 credit card at 24.99% APR ($150/mo minimum), and a $10,500 credit card at 28.99% APR ($230/mo minimum). Together, their required minimums are $520/month, and they have $280/month in extra blitz cash ($800/month total budget).
When they use a Snowball-only app or calculator, it instructs them to spend the first 11 months paying off the 0% medical bill and the 9% personal loan. While they celebrate crossing two low-interest bills off their list, their $10,500 balance at 28.99% APR sits in the background burning $8.34 every single day ($253/month) in pure interest.
By switching to the Debt Avalanche and attacking the 28.99% balance on Day 1, their total interest paid drops from $6,840 down to $3,920—saving $2,920 in cold cash and reaching $0 four months earlier without paying a single extra dollar per month.
How the Two Payoff Engines Work
In both methods, your monthly commitment is identical: you pay the required minimum payment on every account except your single designated Target Account, which receives 100% of your extra monthly surplus cash. When that Target Account hits $0, you roll its entire monthly payment into the next target.
The only difference is how the Target Account is selected:
- The Debt Snowball Method (Behavioral Momentum): You order your debts strictly from smallest dollar balance to largest dollar balance, completely ignoring the interest rate. The goal is psychological reinforcement—knocking out small nuisance balances quickly so you see fewer bills each month.
- The Debt Avalanche Method (Mathematical Optimization): You order your debts strictly from highest APR to lowest APR. By directing every spare dollar at the balance charging 28% or 29.99% APR, you aggressively shrink the principal that generates the highest Daily Interest Bleed.
| Comparison Dimension | Debt Snowball (Smallest Balance First) | Debt Avalanche (Highest APR First) | Cash-Flow Hybrid (LEVEL Dynamic Engine) |
|---|---|---|---|
| Primary Optimization Goal | Fastest first account closure (emotional momentum) | Lowest total interest paid & earliest debt-free date | Balances immediate monthly cash-flow relief with APR eradication |
| Total Interest ($21k Portfolio) | ~$6,840 | ~$3,920 ($2,920 saved) | ~$4,150 (while freeing $55–$140/mo early) |
| Time to Debt-Free | 35 Months | 31 Months (4 months faster) | 31.5 Months |
| Biggest Vulnerability | Leaves 28%–30% APR balances compounding untouched for months or years | If your highest-APR card also has a $12,000 balance, your first account closure takes longer | Requires a dual-engine planner like LEVEL to model accurately |
| When to Choose It | When all your cards have similar APRs (e.g., all between 24% and 26%) or you desperately need to free up a monthly minimum | Whenever there is a 5%+ spread between your highest and lowest interest rates | When you have one tiny high-minimum nuisance card plus a massive high-APR balance |
Why 2026 Interest Rates Broke the Classic Snowball Rule
When the Debt Snowball was popularized on talk radio in the late 1990s and early 2000s, the average credit card interest rate hovered between 12% and 14%. At 12% APR, the dollar difference between paying smallest-balance-first vs. highest-APR-first was often only a few hundred dollars—a reasonable price to pay for a quick psychological boost.
In 2026, revolving credit card APRs routinely sit between 26.99% and 31.99%. At 29% APR, compound daily interest acts like an accelerant. As we showed in our breakdown of the best debt payoff apps without bank linking, apps that lock you into a Snowball-only schedule without showing you the Avalanche alternative hide thousands of dollars in avoidable finance charges.
Not sure which tab to follow? Apply these three objective mathematical rules:
- The 5% APR Spread Rule: If the gap between your highest-APR debt and your lowest-APR debt is 5 percentage points or more (for example, a 28.99% credit card vs. a 7% auto loan or 0% promo balance), always use the Debt Avalanche.
- The Identical Rate Rule: If all of your credit cards sit within a tight 2% band (for example, four cards at 25.99%, 26.49%, 26.99%, and 27.49%), the interest rate difference is negligible—use the Debt Snowball to wipe out the smallest balance first and simplify your monthly bills.
- The Cash-Flow Emergency Exception: If your monthly budget is so tight that you are one flat tire away from missing a payment, use a Cash-Flow Yield strike to eliminate a tiny $400–$800 balance that carries a disproportionate $40–$50 minimum payment, then immediately pivot back to the Debt Avalanche.
How to Supercharge Both Methods: Lower the APR While You Blitz
Whether you choose the Avalanche or the Snowball, your payoff speed multiplies when you compress the interest rate on your largest balances:
- Request an Internal Hardship Rate Cut: Before making your next extra payment, use our scripts for credit card hardship programs to ask your issuer’s Loss Mitigation desk for a 6%–9% fixed workout rate.
- Compare a Nonprofit DMP Quote: If your cards refuse to lower your APR directly, see our math on whether a nonprofit Debt Management Plan is worth it when it drops all your APRs to ~7.5% across the board.
Unlock Your Full 12-Month Payoff Blueprint With LEVEL
Have more than four accounts, variable monthly income, or want to test how a one-time tax refund or hardship APR cut changes your finish line? LEVEL gives you a full Dynamic Blitz Engine—comparing Avalanche, Snowball, and Daily Interest Bleed down to the cent with zero bank logins and zero AI data waivers.
Model Your Full Portfolio in LEVEL →