
Merging Finances (and Debt) Before Marriage: The Pre-Marital Debt Playbook
Marriage is an emotional union, but in the eyes of the law, it is a binding economic merger. When one partner arrives with zero liabilities and the other carries $65,000 in student loans and high-APR credit cards, romantic idealism quickly crashes into harsh legal reality. Discover the statutes governing pre-marital debt, debunk the myth of “merged credit scores,” and implement the 3 account structures that eliminate debt without destroying relationship trust.
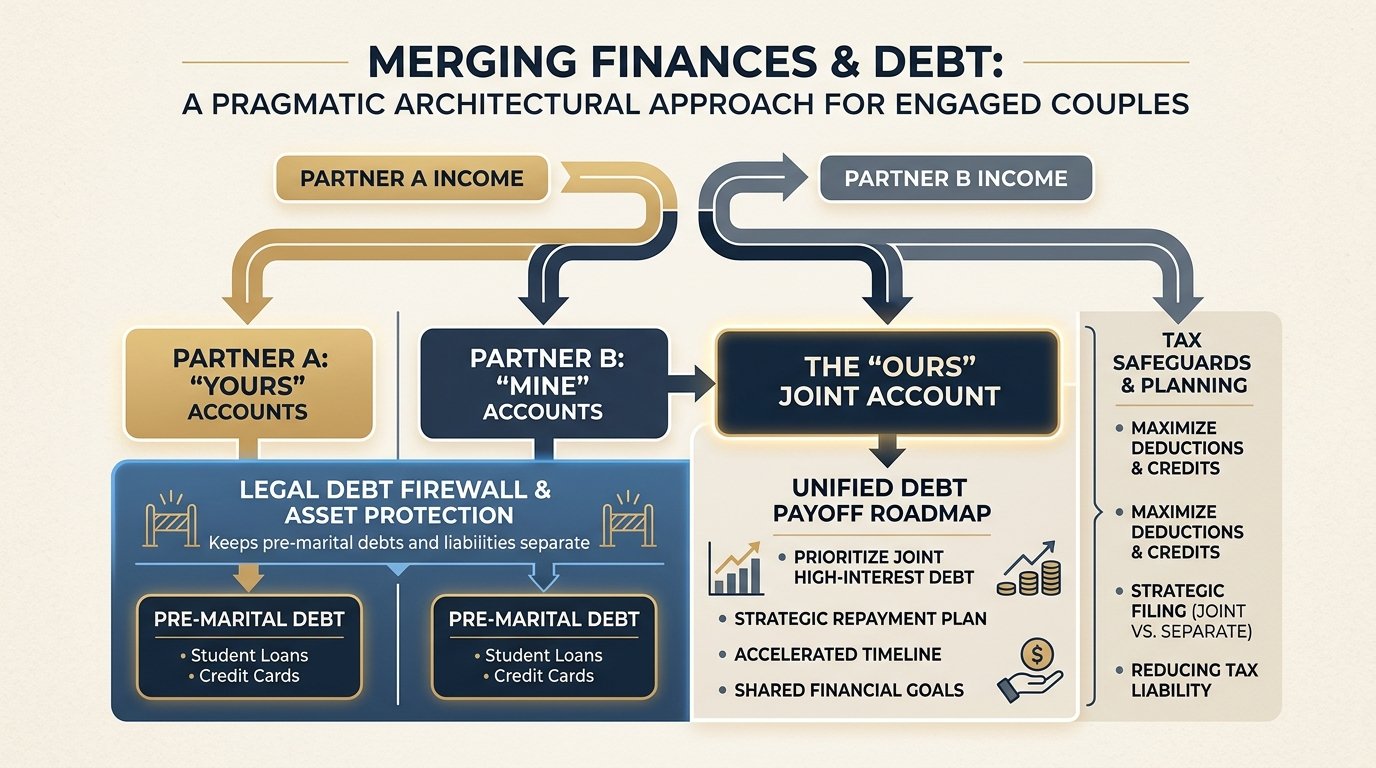
- Pre-Marital Debt Remains Individual: In all 50 states, debts contracted prior to marriage legally belong strictly to the person who incurred them. Your spouse’s pre-marital creditors cannot sue you individually.
- The Co-Mingling Exposure: Depositing joint funds or commingling assets into a single shared account can legally expose both partners’ money to aggressive creditor garnishment, especially in Community Property states.
- Credit Reports Never Merge: Experian, Equifax, and TransUnion maintain distinct files linked to individual Social Security numbers. Your partner’s low credit score will not mathematically drag down your individual score—unless you apply jointly for new credit.
- Never Pay Off a Partner’s Debt Before the Wedding: Legally, paying off an engagement partner’s debt prior to legal marriage is categorized as a non-refundable gift. If the relationship dissolves, those funds cannot be recovered.
- The “Yours, Mine, and Ours” Waterfall: The most sustainable account architecture maintains separate personal checking accounts alongside a shared household hub funded proportionally to income.
1. The Emotional Taboo vs. The Mathematical Reality
According to sociological studies, financial disagreements are the single strongest predictor of marital dissolution—surpassing infidelity, in-law friction, and career disagreements. The primary catalyst is rarely the gross dollar amount of debt itself; it is the asymmetry of expectations and the unspoken shame surrounding pre-existing liabilities.
When couples enter marriage, they often oscillate between two extremes:
- The Ostritch Strategy: Refusing to examine each other’s balances until an unexpected mortgage rejection or collection letter forces an emergency reckoning.
- The Financial Martyr Strategy: The higher-earning or debt-free partner immediately empties their savings to bail out the other partner’s balances, sparking unspoken resentment, guilt, and uneven power dynamics within the relationship.
Healthy financial unions require replacing emotional volatility with structural architecture. Approaching debt as a shared engineering project—rather than a character flaw—transforms a source of friction into your first collaborative triumph as a team.
2. The Legal Truth: Do You Inherit Your Spouse’s Debt?
The most pervasive anxiety among engaged individuals is whether signing a marriage certificate transfers legal responsibility for their fiancé’s prior student loans, auto loans, or credit card debt.
The short answer: No, but the state you live in governs how your joint assets can be targeted.
Common Law Property States (41 States)
In the 41 Common Law states (including New York, Florida, Illinois, Pennsylvania, and Ohio), debt acquired by one spouse before the marriage remains exclusively that spouse’s separate liability. Creditors cannot touch your individual bank accounts, individual investments, or individual paychecks to satisfy your partner’s pre-marital debts.
However, if you open a joint checking account and deposit your personal salary into it, you have commingled funds. A creditor with a judgment against your spouse can legally freeze and levy that joint account—taking your hard-earned wages to satisfy their debt.
Community Property States (9 States)
In the 9 Community Property states—Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin—the statutory landscape is significantly more aggressive.
While pre-marital debt remains classified as “separate debt” upon marriage, any income earned by either spouse during the marriage is classified as community property.
In states like California (under California Family Code § 910), community property is liable for a debt incurred by either spouse before or during marriage. This means if your spouse owes $30,000 in pre-marital credit card debt and enters default, the creditor can pursue community property—including income earned by the debt-free spouse—to satisfy the judgment!
The Statutory Safe Harbor: To insulate the non-debtor spouse’s wages in California and several other community property jurisdictions, those wages must be deposited directly into a separate bank account held solely in the non-debtor spouse’s name, to which the debtor spouse has no access or signature authority.
3. Credit Scores and Marriage: Debunking the “Blended Credit” Myth
A common misconception is that marriage generates a combined household credit score or averages your scores together.
In reality, credit bureaus (Experian, TransUnion, Equifax) do not track marital status. There is no such thing as a “joint credit report.” Your credit history remains indexed exclusively to your nine-digit Social Security number.
How Your Partner’s Score Still Affects You:
- Joint Mortgage Applications: When applying jointly for a home loan, mortgage underwriters pull all three bureau scores for both applicants. In conventional lending, lenders evaluate the lower of the two mid-scores. If your mid-score is 790 and your partner’s mid-score is 620, the entire mortgage approval and interest rate are benchmarked against the 620.
- Co-Signing Exposure: If you co-sign a consolidation loan or auto note to help your spouse refinance, that liability reports 100% to both of your credit files. If a payment is missed, your credit score suffers identical catastrophic damage.
- Authorized User Spillover: Adding your partner as an authorized user on your pristine credit card can help rehabilitate their score by importing your on-time history. However, adding yourself to their maxed-out card will immediately import their high credit utilization ratio onto your report, instantly depressing your FICO score.
4. The Pre-Marital Financial Disclosure Audit
Before printing wedding invitations or signing catering contracts, schedule a formal “Financial Disclosure Audit.” This is not an emotional interrogation; it is a clinical balance-sheet reconciliation.
Both partners should sit down with complete documentation and disclose the following six data points across every active account:
Total exact balance on every credit card, personal loan, student loan, vehicle note, medical obligation, and IRS back-tax liability.
Identify which debts carry toxic high interest (22%–29% APR cards) versus manageable fixed rates (4%–6% federal student loans). Calculate your combined daily interest bleed ($/day leaving the household).
Calculate the combined contractual minimum cash flow required just to prevent default each month. This forms the baseline floor of your future household budget.
Pull official, free annual credit reports from AnnualCreditReport.com. Verify that neither partner has unknown collections, charge-offs, or identity theft discrepancies lurking in their files.
Disclose whether any creditor has initiated legal action, filed a wage garnishment motion, or placed a lien on personal assets.
Audit how much actual cash is available in checking and high-yield savings to determine if you have an adequate starter safety cushion (as detailed in our guide on emergency funds vs. debt payoff).
5. The 3 Bank Account Architectures for Couples with Debt
How should you structure your daily banking when one partner owes significantly more debt than the other? There are three distinct operating architectures:
| Architecture | Structure Overview | Best Suited For | Primary Vulnerability |
|---|---|---|---|
| 1. The Total Pool (All-In) |
100% of both incomes deposit into a single joint checking account. All bills and debt payments draw from this single pool. | Couples with equal liabilities, similar financial philosophies, and zero active collection threats. | Sparks acute resentment if one partner pays off the other’s heavy discretionary debt while sacrificing personal goals. |
| 2. The Proportional Waterfall (Yours, Mine & Ours) |
Paychecks deposit into separate individual accounts. Each transfers a proportional percentage into a Joint Account for shared living costs. Personal debt is serviced from individual accounts. | Couples with significant debt asymmetry or divergent income levels. (Recommended for 80% of couples). | Requires monthly coordination and clear definitions of what qualifies as a “joint” vs. “personal” expense. |
| 3. The Strict Firewall (Total Separation) |
Zero joint accounts. Each partner retains 100% separate accounts and transfers exact dollar shares of rent/utilities via Venmo or Zelle. | High-risk situations: active creditor lawsuits, tax levies, or business liability exposure. | Feels transactional and hinders long-term unified wealth accumulation. |
Deep-Dive: How to Implement the Proportional Waterfall
The Proportional Waterfall preserves relational peace by maintaining individual autonomy while fostering partnership on shared responsibilities.
Scenario: Partner A earns $6,000/month take-home and has $0 debt. Partner B earns $4,000/month take-home and carries $28,000 in high-interest debt (requiring $750/month in minimum payments). Shared household expenses (rent, groceries, utilities, joint savings) total $4,500/month.
- Total Household Income: $10,000/month.
- Partner A earns 60% ($6,000 / $10,000).
- Partner B earns 40% ($4,000 / $10,000).
Instead of splitting shared household costs 50/50 (which would leave Partner B with almost zero breathing room after their $750 debt payment), they fund the Joint Account proportionally:
- Partner A transfers: 60% of $4,500 = $2,700 into Joint Account. (Partner A retains $3,300 in personal checking).
- Partner B transfers: 40% of $4,500 = $1,800 into Joint Account. (Partner B retains $2,200 in personal checking).
Partner B now uses their remaining $2,200 to cover their $750 debt obligation plus aggressive extra principal payments, while Partner A retains full control over their surplus savings. Neither feels exploited, and both are pulling their equitable weight.
6. Should You Pay Off Your Partner’s Debt Before the Wedding?
It is common for a financially secure partner to offer: “I have $30,000 sitting in my high-yield savings account earning 4.5%. Why let your cards bleed at 24% APR? Let me just write a check and wipe it out today before the wedding.”
From a pure interest-rate perspective, paying off a 24% card saves immediate money. From a legal and relationship risk perspective, paying off substantial debt prior to the wedding is extraordinarily dangerous.
Under federal and state law, any money transferred to pay off another individual’s debt before legal marriage is classified as an irrevocable gift.
If the engagement ends, the relationship breaks down, or the wedding is canceled, the contributing partner has zero legal right to reclaim that money—unless both parties signed a legally binding, notarized Promissory Note beforehand establishing it as an enforceable personal loan.
The Best Practice: Keep your cash in your high-yield savings account until the marriage certificate is signed and filed. If you still choose to deploy those savings post-wedding, do so as legal spouses within a shared household roadmap.
7. Building a Unified Debt Elimination Machine
Once married, attack remaining liabilities as a synchronized unit. How you organize the attack depends on your psychological and mathematical priorities:
Stack all household debts in order of interest rate, regardless of whose name is on the account. Channel all extra surplus cash into the highest-APR card while paying contractual minimums on everything else. This mathematically minimizes the daily interest bleed leaving your joint household.
If one partner suffers severe financial anxiety from having multiple creditors calling, use the Debt Snowball to target the smallest balances first. Eliminating 2 or 3 small accounts quickly wipes out their mandatory monthly minimums, immediately expanding monthly cash flow breathing room.
Rather than arguing over subjective spreadsheet formulas, couples can use LEVEL to model dynamic scenarios together. Test what happens if you apply a tax refund, shift extra payments between accounts, or model irregular freelance income—watching your unified debt-free date compress in real time on an objective visual roadmap.
8. The Engaged Couple’s Debt Elimination Checklist
- [ ] Complete the Disclosure Audit: Exchange full statements showing balances, APRs, minimums, and credit reports with zero judgment.
- [ ] Check State Property Statutes: Determine whether you reside in a Common Law or Community Property state to understand debt liability rules.
- [ ] Select Your Account Architecture: Agree explicitly on whether you will operate an All-In, Proportional Waterfall, or Strict Firewall banking model.
- [ ] Establish a Joint Emergency Floor: Ensure at least 1 to 2 months of joint survival expenses are protected in cash before making aggressive lump-sum payoff moves.
- [ ] Hold Off on Pre-Wedding Payoffs: Do not transfer personal savings to clear fiancé debts prior to the legal wedding ceremony without a formal promissory note.
- [ ] Schedule a Monthly “Money Date”: Dedicate 30 minutes on the first Sunday of each month to review payoff progress objectively using a visual tool.
Architect Your Unified Debt-Free Roadmap Together
Eliminate money arguments with mathematical certainty. LEVEL allows couples to model joint payoff scenarios, track multi-account velocity, and engineer the exact month you hit zero—without ever linking bank accounts or sharing sensitive financial passwords.
Model Your Payoff at DebtFreeArchitect.com →Available on desktop and on the go via the newly launched LEVEL Mobile View. 100% private. Zero bank credentials required.